Contribution limits guide · Updated November 2026
For 2027, a participant may defer up to $25,500 to a 401(k), 403(b) or governmental 457(b) plan, with an additional $8,500 catch-up at age 50 and over. Total annual additions to one account are capped at $75,000, and the IRA limit remains $7,500. The deferral, catch-up and annual additions figures are each up from 2026, while the IRA limit is unchanged.
The limits are adjusted each autumn for the following year. The 2027 amounts come from Notice 2026-66, which the IRS announced in IR-2026-136 on November 12, 2026, and they will appear in the IRS cost-of-living table. The tables below give the 2027 figure alongside the 2026 figure it replaced, so the change is visible rather than assumed.
Three developments matter more than the inflation adjustments this year: both age-based catch-ups rose, including the age 60 to 63 catch-up that held steady for 2026; the IRA limits held at their 2026 levels; and the Saver’s Match replaces the Saver’s Credit for contributions to workplace plans and IRAs. Those are covered below the tables, along with the higher Roth catch-up wage threshold.
2027 Contribution Limits at a Glance
| Limit | 2027 | 2026 |
|---|---|---|
| Elective deferrals, 401(k), 403(b), governmental 457(b), section 402(g) | $25,500 | $24,500 |
| Catch-up contributions, age 50 and over | $8,500 | $8,000 |
| Catch-up contributions, ages 60 to 63 | $11,750 | $11,250 |
| Deferrals plus catch-up, age 50 and over | $34,000 | $32,500 |
| Deferrals plus catch-up, ages 60 to 63 | $37,250 | $35,750 |
| Annual additions to one account, section 415(c) | $75,000 | $72,000 |
| Compensation taken into account, section 401(a)(17) | $375,000 | $360,000 |
| IRA contributions, traditional and Roth | $7,500 | $7,500 |
| IRA catch-up, age 50 and over | $1,100 | $1,100 |
Every limit above is published in Notice 2026-66, which states each 2027 amount alongside the 2026 amount it replaced. The combined totals are the sums of those limits, and IR-2026-136 states the $34,000 total for participants aged 50 and over.
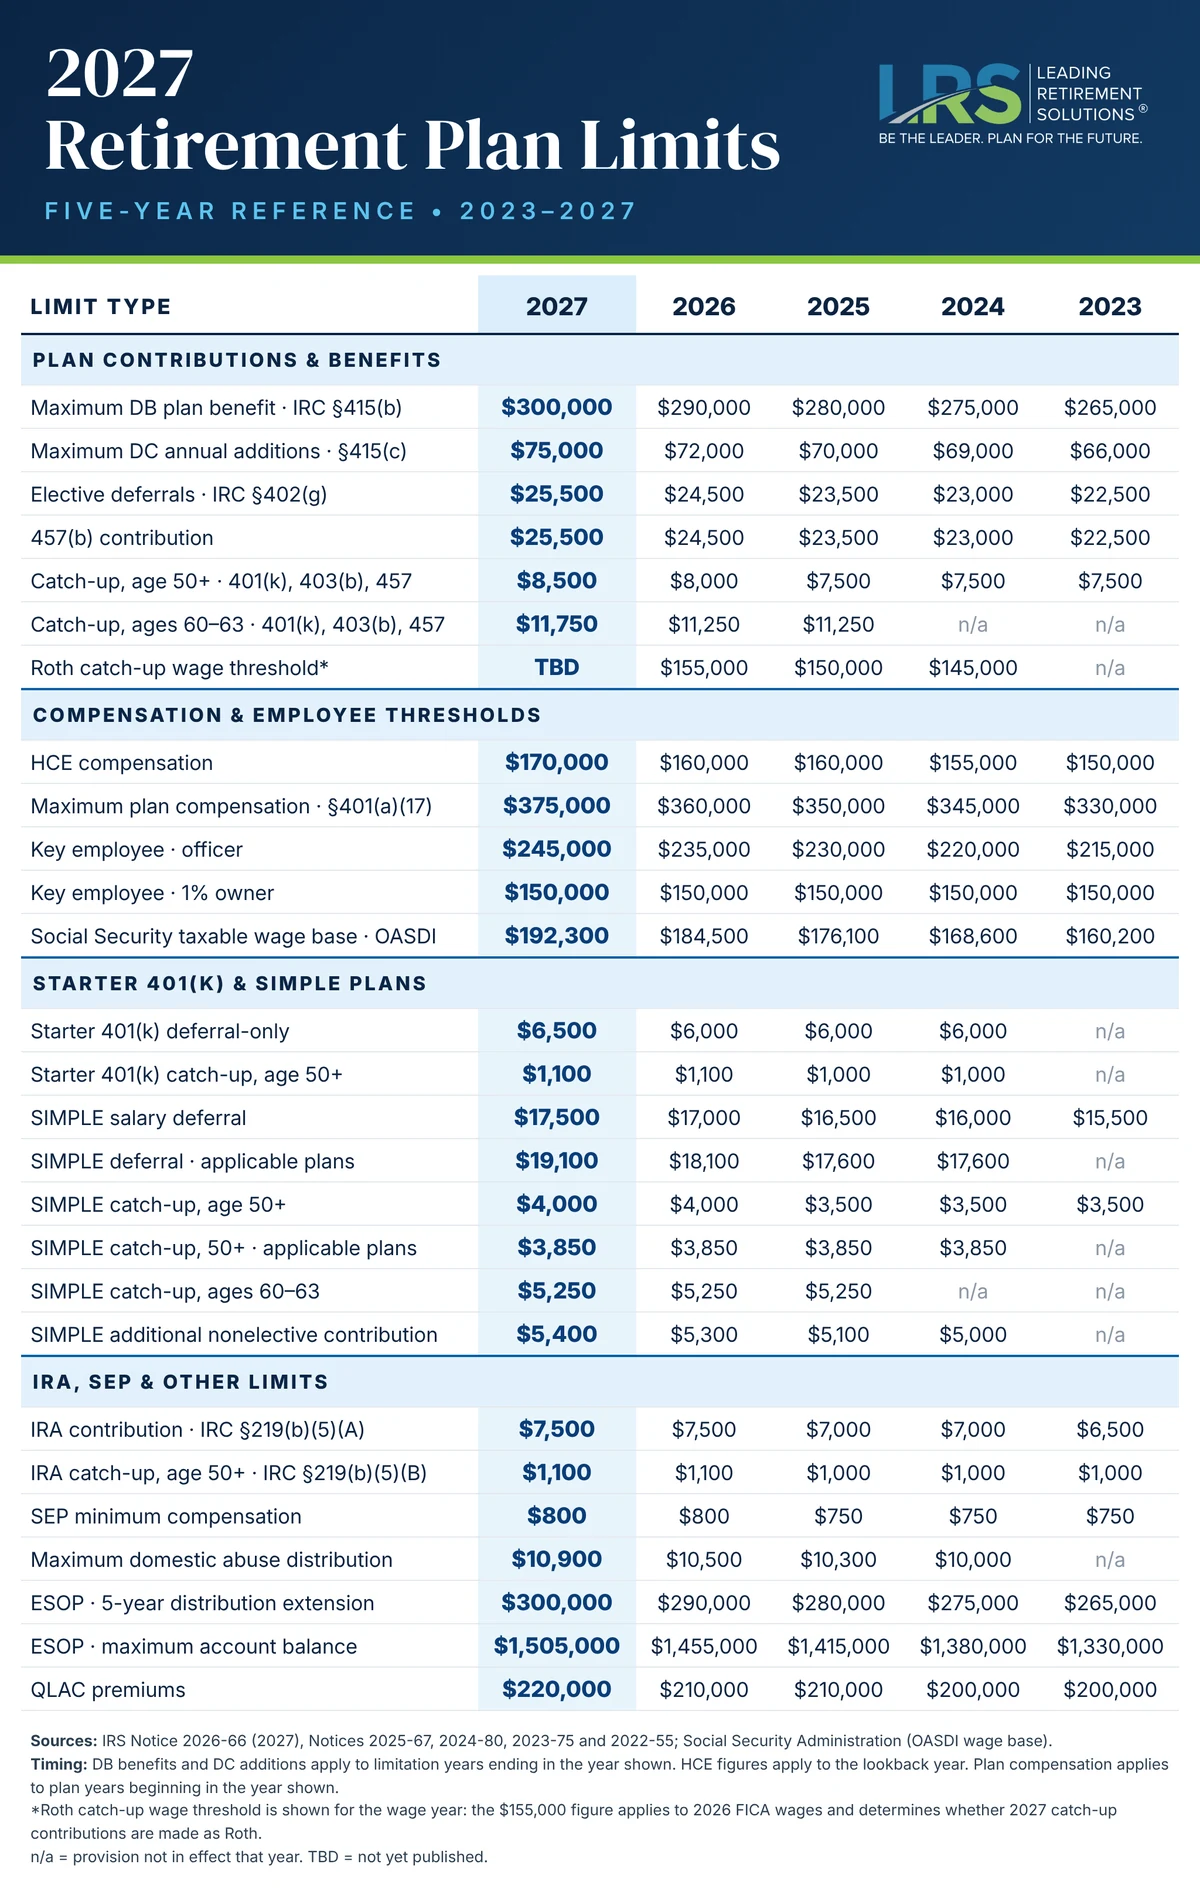
IRS Retirement Plan Limits, 2023 to 2027
The table below lists the dollar limits and thresholds that most often come up in plan administration, for each year from 2023 through 2027. Figures for 2027 come from Notice 2026-66; earlier years come from Notice 2025-67, Notice 2024-80, Notice 2023-75, Notice 2022-55, and the IRS cost-of-living table.
| Limit type | 2027 | 2026 | 2025 | 2024 | 2023 |
|---|---|---|---|---|---|
| Maximum defined benefit plan benefit, IRC §415(b) (limitation years ending in the year shown) | $300,000 | $290,000 | $280,000 | $275,000 | $265,000 |
| Maximum defined contribution annual additions, IRC §415(c) (limitation years ending in the year shown) | $75,000 | $72,000 | $70,000 | $69,000 | $66,000 |
| Elective deferral limit, IRC §402(g) | $25,500 | $24,500 | $23,500 | $23,000 | $22,500 |
| Catch-up limit for 401(k), 403(b), and 457 plans, age 50 and over (calendar year) | $8,500 | $8,000 | $7,500 | $7,500 | $7,500 |
| Catch-up limit for 401(k), 403(b), and 457 plans, ages 60 to 63 (calendar year) | $11,750 | $11,250 | $11,250 | n/a | n/a |
| Roth catch-up wage threshold, IRC §414(v)(7)(A) (applied to wages for the year shown) | TBD | $155,000 | $150,000 | $145,000 | n/a |
| Highly compensated employee compensation (lookback year shown) | $170,000 | $160,000 | $160,000 | $155,000 | $150,000 |
| Maximum plan compensation, IRC §401(a)(17) (plan years beginning in the year shown) | $375,000 | $360,000 | $350,000 | $345,000 | $330,000 |
| Key employee: officer | $245,000 | $235,000 | $230,000 | $220,000 | $215,000 |
| Key employee: 1% owner | $150,000 | $150,000 | $150,000 | $150,000 | $150,000 |
| Social Security taxable wage base (OASDI) | $192,300 | $184,500 | $176,100 | $168,600 | $160,200 |
| Maximum domestic abuse distribution, IRC §72(t)(2)(K)(ii)(I) | $10,900 | $10,500 | $10,300 | $10,000 | n/a |
| 457(b) contribution limit | $25,500 | $24,500 | $23,500 | $23,000 | $22,500 |
| Starter 401(k) deferral-only arrangement limit | $6,500 | $6,000 | $6,000 | $6,000 | n/a |
| Starter 401(k) deferral-only catch-up, age 50 and over | $1,100 | $1,100 | $1,000 | $1,000 | n/a |
| SIMPLE salary deferral limit | $17,500 | $17,000 | $16,500 | $16,000 | $15,500 |
| SIMPLE salary deferral limit, applicable plans (25 or fewer employees, or employer elects higher contributions), IRC §408(p)(2)(E)(i)(I) | $19,100 | $18,100 | $17,600 | $17,600 | n/a |
| SIMPLE catch-up limit, age 50 and over | $4,000 | $4,000 | $3,500 | $3,500 | $3,500 |
| SIMPLE catch-up limit, age 50 and over, applicable plans, IRC §414(v)(2)(B)(iii) | $3,850 | $3,850 | $3,850 | $3,850 | n/a |
| SIMPLE catch-up limit, ages 60 to 63 | $5,250 | $5,250 | $5,250 | n/a | n/a |
| SIMPLE additional nonelective contribution limit, IRC §408(p)(2)(A)(iv) | $5,400 | $5,300 | $5,100 | $5,000 | n/a |
| IRA contribution limit, IRC §219(b)(5)(A) | $7,500 | $7,500 | $7,000 | $7,000 | $6,500 |
| IRA catch-up limit, age 50 and over, IRC §219(b)(5)(B) | $1,100 | $1,100 | $1,000 | $1,000 | $1,000 |
| SEP minimum compensation threshold | $800 | $800 | $750 | $750 | $750 |
| ESOP: 5-year distribution period extension amount | $300,000 | $290,000 | $280,000 | $275,000 | $265,000 |
| ESOP: maximum account balance for 5-year distribution period | $1,505,000 | $1,455,000 | $1,415,000 | $1,380,000 | $1,330,000 |
| Premiums for qualifying longevity annuity contracts (QLACs), Treas. Reg. §1.401(a)(9)-6(q)(2)(ii) | $220,000 | $210,000 | $210,000 | $200,000 | $200,000 |
n/a: the provision was not in effect for that year. The Roth catch-up wage threshold is applied to the prior year’s FICA wages: the $155,000 figure shown for 2026 applies to 2026 wages and determines whether catch-up contributions made in 2027 are designated as Roth contributions. The figure applied to 2027 wages, for catch-up contributions made in 2028, had not been published as of November 2026. The 1% owner key employee amount is set by statute and is not adjusted for inflation. The Social Security taxable wage base is set by the Social Security Administration and is shown for reference.
Catch-Up Contributions, and the Roth Requirement That Applies
Both catch-ups rose for 2027
The catch-up limit for participants aged 50 and over is $8,500 for 2027, up from $8,000. The higher catch-up for participants who turn 60, 61, 62 or 63 during the year is $11,750, up from $11,250, after holding at the same figure for 2025 and 2026.
The age-based figures do not stack. A participant who turns 60 through 63 during 2027 uses the $11,750 figure instead of the $8,500 figure, not in addition to it. A participant who turns 64 during the year returns to the $8,500 catch-up. The IRS sets this out on its catch-up contributions page.
Higher earners make catch-up contributions on a Roth basis
The Roth catch-up requirement, which took full effect for 2026, continues to apply. For 2027, a participant whose 2026 FICA wages from the plan’s sponsoring employer exceeded $155,000 makes catch-up contributions as designated Roth contributions. The threshold was $145,000 as originally enacted and is adjusted for inflation; it was $150,000 for catch-up contributions made in 2026.
Two practical points follow. The test uses Social Security wages from the sponsoring employer for the prior year, which appears in Box 3 of the participant’s Form W-2, rather than total compensation or wages from another employer. Participants whose catch-up contributions must be made on a Roth basis may be affected if the plan does not currently offer a designated Roth feature. How the requirement is implemented depends on the plan’s provisions and any required amendments.
403(b) and 457(b) Plans: Two Additional Catch-Ups
Both plan types share the $25,500 deferral limit and the age-based catch-ups above. Each also has a further catch-up of its own, which is where the arithmetic stops matching a 401(k).
The 403(b) fifteen-year service catch-up
Employees with at least fifteen years of service with certain employers may be eligible to make additional contributions to a 403(b) plan beyond the regular age 50 catch-up. The IRS notes the provision on its catch-up contributions page. Eligibility depends on the type of employer, the service history, and amounts contributed in prior years, so it is calculated for the individual rather than applied as a flat figure.
The 457(b) pre-retirement catch-up
A governmental 457(b) plan may permit a special catch-up in the three years before the participant’s normal retirement age under the plan, allowing up to twice the annual deferral limit. On the 2027 figure that is $51,000. It cannot be combined with the age 50 catch-up in the same year: a participant eligible for both uses whichever is greater.
SIMPLE Plan Limits
| SIMPLE limit | 2027 | 2026 |
|---|---|---|
| Employee contributions | $17,500 | $17,000 |
| Employee contributions, certain applicable plans | $19,100 | $18,100 |
| Catch-up, age 50 and over | $4,000 | $4,000 |
| Catch-up, age 50 and over, certain applicable plans | $3,850 | $3,850 |
| Catch-up, ages 60 to 63 | $5,250 | $5,250 |
| Additional nonelective contribution | $5,400 | $5,300 |
The two-tier structure comes from SECURE 2.0, which permits a higher contribution amount for certain applicable SIMPLE plans. Which tier applies to a given plan depends on conditions in the statute rather than on an employer election alone, and the IRS sets out the SIMPLE rules for smaller employers in Publication 560. For 2027, both employee contribution amounts rose, while all three SIMPLE catch-up amounts are unchanged.
SEP and Other Employer Plan Thresholds
| 2027 threshold | Amount | What it applies to |
|---|---|---|
| SEP maximum contribution | $75,000 | The same figure as the section 415(c) annual additions limit |
| SEP compensation cap | $375,000 | The same figure as the section 401(a)(17) compensation limit |
| SEP minimum compensation for participation | $800 | The earnings threshold at which an employee becomes eligible |
| Highly compensated employee threshold | $170,000 | Applied to compensation for a plan year to determine status for the following plan year, used in ADP and ACP testing |
| Key employee threshold | $245,000 | Used in the top-heavy determination under Code section 416 |
| Annual benefit, defined benefit plan, section 415(b) | $300,000 | The limit on the benefit payable, the mirror of the annual additions limit |
Ownership is a separate route to highly compensated employee status, independent of pay, so the $170,000 figure does not settle the question on its own. Testing is covered in our overview of defined contribution plans, and a safe harbor design removes the ADP test where its conditions are met.
Other Figures That Come Up in Plan Administration
Two further sets of figures come up in plan administration, though neither is a contribution limit.
The Social Security taxable wage base is $192,300 for 2027, as set by the Social Security Administration. It matters here because integrated or permitted disparity allocation formulas use it, and because the Roth catch-up test runs on FICA wages rather than total compensation.
The employee stock ownership plan figures are $1,505,000 and $300,000 for 2027. These are the amounts used in applying the distribution period rules under Code section 409(o), and they apply to plans holding qualifying employer securities.
The Saver’s Match and the Saver’s Credit
For taxable years beginning after December 31, 2026, Saver’s Match contributions under Code section 6433 replace the Saver’s Credit for elective contributions made to qualifying retirement plans and IRAs. The Saver’s Credit continues to be available for contributions to ABLE accounts. Notice 2026-66 points to Notice 2026-48 for guidance on the change.
The 2027 Saver’s Credit income limits, which apply to ABLE account contributions, are:
| Filing status | 2027 income limit | 2026 |
|---|---|---|
| Married filing jointly | $83,000 | $80,500 |
| Head of household | $62,250 | $60,375 |
| Single, and married filing separately | $41,500 | $40,250 |
What Changed for 2027
- Elective deferrals rose $1,000 to $25,500, and annual additions rose $3,000 to $75,000.
- Both age-based catch-ups rose. The age 50 catch-up rose from $8,000 to $8,500, and the age 60 to 63 catch-up from $11,250 to $11,750 after holding steady for 2026.
- The IRA limits held steady. The IRA contribution limit remains $7,500 and the IRA catch-up remains $1,100.
- The Roth catch-up wage threshold rose to $155,000. It applies to 2026 FICA wages and determines whether 2027 catch-up contributions are made on a Roth basis.
- The Saver’s Match replaces the Saver’s Credit for elective contributions to qualifying retirement plans and IRAs, while the Saver’s Credit continues for ABLE account contributions.
- SIMPLE employee contribution amounts moved on both tiers, with the standard limit rising to $17,500 and the higher applicable amount to $19,100. The SIMPLE catch-up amounts are unchanged.
- Compensation and testing thresholds rose. The compensation cap moved to $375,000, the highly compensated employee threshold to $170,000, and the key employee threshold to $245,000.
Provisions that took effect in earlier years continue to apply, including the age 60 to 63 catch-up, the Roth catch-up requirement, the automatic enrollment requirement for plans established after December 29, 2022, covered in our article on automatic enrollment, and the reduced service condition for long-term part-time employees.
How the Limits Work Together
One participant, several plans
The section 402(g) deferral limit follows the individual for the calendar year. The section 415(c) annual additions limit applies per plan, subject to aggregation rules that treat related employers as a single employer. A participant with genuinely unrelated employers can therefore have two separate $75,000 limits but only one $25,500 deferral limit.
The compensation cap changes the formula, not the contribution
The $375,000 compensation limit is often read as a cap on what a highly paid participant can receive. It is not. It caps the compensation figure a plan may use in its allocation formula. A plan contributing 10 percent of pay allocates 10 percent of $375,000 for a participant earning $500,000, not 10 percent of $500,000. The participant can still receive up to the full $75,000 in annual additions if other contribution sources reach it.
The limits are per participant, and monitored per payroll
The deferral limit applies to the individual and the annual additions limit to the account, so neither is tested at the plan level. In practice both are monitored across the year rather than checked once, because a participant who front-loads deferrals can reach the section 402(g) limit before the final payroll and, in a plan whose match is calculated per pay period without a true-up, stop receiving match for the remainder of the year. Whether a plan trues up at year end is a plan document question.
Employer deductions are a separate limit
Code section 404 limits what an employer may deduct for contributions to a qualified plan for a taxable year, and that limit is calculated differently from the section 415(c) annual additions limit. A contribution can be within the annual additions limit and still exceed the deduction limit. The IRS covers the deduction rules for smaller employers in Publication 560.
Correcting an excess
Where deferrals across all plans exceeded the section 402(g) limit for a calendar year, the excess and its earnings are distributed by April 15 of the following year. That deadline and the rest of the plan year calendar are set out in our guide to retirement plan deadlines. Where a limit was exceeded and not corrected in time, the IRS correction routes are described in its 401(k) Plan Fix-It Guide and our consulting and correction services cover the formal programs.
Where the limits come from
The deferral limit is set by Code section 402(g) and the annual additions and benefit limits by Code section 415, which requires the amounts to be adjusted annually for cost-of-living increases. That is why the figures change most years and occasionally hold steady: the adjustment is formula-driven and rounds to set increments, so a limit can stay flat when the calculated increase does not clear the rounding threshold. The IRA limit holding at $7,500 for 2027 is an example.
When the Next Update Comes
The IRS publishes the following year’s limits in the autumn, generally late October or early November, in a notice numbered for that year and an accompanying news release. The 2028 figures will appear on the same cost-of-living page when they are released, and this article is updated at that point rather than replaced.
Applying the current limits correctly across deferrals, matching, profit sharing and testing is part of ongoing plan administration and recordkeeping. For employers considering a plan or a different design, establishing a new plan and changing an existing one cover the options, and our team can help employers understand how current contribution limits may apply to their retirement plan and administrative processes.
Questions That Come Up on Contribution Limits
What is the 401(k) contribution limit for 2027?
$25,500 in elective deferrals, up from $24,500 for 2026. Participants aged 50 and over may contribute an additional $8,500, for a total of $34,000. Participants who turn 60, 61, 62 or 63 during 2027 may contribute an additional $11,750 instead, for a total of $37,250. The figures come from Notice 2026-66, announced in IR-2026-136.
What is the total 401(k) contribution limit including employer contributions?
$75,000 for 2027, up from $72,000 for 2026. This is the section 415(c) annual additions limit and it covers everything allocated to one participant’s account for the year: elective deferrals, employer matching and nonelective contributions, after-tax contributions, and reallocated forfeitures. Catch-up contributions sit outside it, so a participant eligible for the age 50 catch-up can receive up to $83,500 in total.
What is the IRA contribution limit for 2027?
$7,500 for traditional and Roth IRAs combined, the same as 2026, with an additional $1,100 catch-up contribution at age 50 and over, also unchanged. The IRA catch-up is indexed for inflation under SECURE 2.0, having been fixed at $1,000 for many years. The IRA limit is separate from the workplace plan deferral limit.
Do I have to make catch-up contributions as Roth in 2027?
If 2026 FICA wages from the plan’s sponsoring employer exceeded $155,000, then yes. Catch-up contributions are made as designated Roth contributions for those participants. The test uses Social Security wages from the sponsoring employer for the prior year, shown in Box 3 of the Form W-2, rather than total compensation or wages from a different employer. Participants whose catch-up contributions must be made on a Roth basis may be affected if the plan does not currently offer a designated Roth feature. How the requirement is implemented depends on the plan’s provisions and any required amendments.
What is the catch-up contribution limit for ages 60 to 63?
$11,750 for 2027, up from $11,250 for 2026. It replaces the $8,500 standard catch-up rather than adding to it, so the combined figure is $37,250. A participant who turns 64 during the year returns to the $8,500 catch-up. The higher limit applies to most 401(k), 403(b) and governmental 457(b) plans.
What is the highly compensated employee threshold for 2027?
$170,000. The figure is applied to compensation for a plan year to determine highly compensated status for the following plan year, and it is used in ADP and ACP nondiscrimination testing. Ownership is a separate route to the same status, independent of pay, so the dollar figure does not settle the question on its own.
What is the SIMPLE plan contribution limit for 2027?
$17,500 for most SIMPLE plans, up from $17,000, with a catch-up of $4,000 at age 50 and over and $5,250 for ages 60 to 63. A higher amount of $19,100 applies to certain applicable SIMPLE plans under a change made by SECURE 2.0, with a catch-up of $3,850 at age 50 and over for those plans.
What is the compensation limit for 2027?
$375,000, up from $360,000 for 2026. This is the section 401(a)(17) limit on the amount of compensation that may be taken into account in a plan’s contribution and allocation formulas. Compensation above the cap is disregarded for that purpose, which is what prevents a formula expressed as a percentage of pay from producing an unlimited allocation.
What happened to the Saver’s Credit for 2027?
For taxable years beginning after December 31, 2026, Saver’s Match contributions under Code section 6433 replace the Saver’s Credit for elective contributions to qualifying retirement plans and IRAs. The Saver’s Credit continues for contributions to ABLE accounts, with 2027 income limits of $83,000 for married couples filing jointly, $62,250 for heads of household, and $41,500 for single filers and married individuals filing separately.
When are the 2028 contribution limits announced?
The IRS publishes the following year’s limits in the autumn, generally late October or early November, in an annual notice and an accompanying news release. They appear on the IRS cost-of-living page at the same time.
What happens if I contribute more than the limit?
Where elective deferrals across all plans exceeded the section 402(g) limit for a calendar year, the excess and its earnings are distributed by April 15 of the following year. This most often affects participants who changed jobs during the year, because the limit follows the individual and neither plan necessarily sees the combined total. Where an excess was not corrected in time, the IRS maintains correction programs for the plan.
Sources
Every substantive statement above is drawn from the following. Links were verified at the time of writing.
- Internal Revenue ServiceNotice 2026-66, 2027 Amounts Relating to Retirement Plans and IRAsThe notice setting the 2027 cost-of-living adjustments. Every 2027 figure in this article, other than the Social Security wage base, comes from here, along with the 2026 comparison figures it states.https://www.irs.gov/pub/irs-drop/n-26-66.pdf
- Internal Revenue ServiceIR-2026-136, 401(k) limit increases to $25,500 for 2027, IRA limit remains $7,500The announcement of the 2027 amounts.https://www.irs.gov/newsroom/401k-limit-increases-to-25500-for-2027-ira-limit-remains-7500
- Internal Revenue ServiceCOLA increases for dollar limitations on benefits and contributionsThe published table of annual limits.https://www.irs.gov/retirement-plans/cola-increases-for-dollar-limitations-on-benefits-and-contributions
- Internal Revenue ServiceNotice 2026-48Guidance on the Saver’s Match, referenced in Notice 2026-66.https://www.irs.gov/pub/irs-drop/n-26-48.pdf
- Internal Revenue ServiceNotice 2025-67The 2026 cost-of-living adjustments.https://www.irs.gov/pub/irs-drop/n-25-67.pdf
- Internal Revenue ServiceNotice 2024-80The 2025 cost-of-living adjustments, including the Roth catch-up wage threshold, SIMPLE, starter 401(k), and domestic abuse distribution amounts.https://www.irs.gov/pub/irs-drop/n-24-80.pdf
- Internal Revenue ServiceNotice 2023-75The 2024 cost-of-living adjustments.https://www.irs.gov/pub/irs-drop/n-23-75.pdf
- Internal Revenue ServiceNotice 2022-55The 2023 cost-of-living adjustments.https://www.irs.gov/pub/irs-drop/n-22-55.pdf
- Social Security AdministrationContribution and benefit baseThe Social Security taxable wage base for 2027 and prior years.https://www.ssa.gov/oact/cola/cbb.html
- Internal Revenue ServiceRetirement topics: catch-up contributionsThe age 50 catch-up, the age 60 to 63 catch-up, and how the two interact.https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-catch-up-contributions
- Internal Revenue ServiceRetirement topics: contributionsHow the contribution types are treated and how the deferral and annual additions limits operate.https://www.irs.gov/retirement-plans/plan-participant-employee/retirement-topics-contributions
- Internal Revenue Service401(k) plan overviewPlan features and the testing the limits feed into.https://www.irs.gov/retirement-plans/plan-sponsor/401k-plan-overview
- Internal Revenue ServiceTypes of retirement plansThe plan structures the limits apply across.https://www.irs.gov/retirement-plans/plan-sponsor/types-of-retirement-plans
- Internal Revenue ServicePublication 560, Retirement Plans for Small BusinessThe SEP and SIMPLE rules, and the deduction limits for smaller employers.https://www.irs.gov/publications/p560
- Internal Revenue Service401(k) Plan Fix-It GuideHow to find, fix and avoid a failure to adhere to the section 402(g) limit and the other common operational mistakes.https://www.irs.gov/retirement-plans/401k-plan-fix-it-guide
- United States Code26 U.S.Csection 415, the annual additions and benefit limits, and section 402, the elective deferral rules. The statutory basis for the limits and for the annual cost-of-living adjustment.https://uscode.house.gov/view.xhtml?req=granuleid%3AUSC-prelim-title26-section415&num=0&edition=prelim