ROBS 401(k) Exit Strategy: What Leaving the Plan Actually Involves
A ROBS plan owns stock in your company. Exiting means turning that stock back into retirement money, or moving it out of the plan, and each route has its own valuation, tax and filing consequences.
A ROBS plan is exited by removing the employer stock from the plan and distributing or rolling over what is left. There are four common routes: selling the business, having the company redeem the stock from the plan, distributing the stock in kind to the participant, or terminating the plan after the stock has been dealt with. Each route depends on a current valuation of the stock, and each has different tax and reporting consequences.
Leading Retirement Solutions · Updated for 2026
Most articles about exiting a ROBS describe it as a single event. In practice it is a sequence, and the order matters, because the plan cannot distribute what it cannot value and the company cannot buy back what it cannot fund.
This guide covers what exiting actually involves, the four routes and what each one triggers, why a required minimum distribution can force a partial exit before the owner is ready, the valuation step every route depends on, the prohibited transaction rules that limit who may buy the stock, and what plan termination involves once the stock is out. It is general information about how these arrangements work rather than advice on any particular plan, and outcomes depend on the plan document and the facts of each business.
What Exiting a ROBS Plan Actually Means
In a ROBS arrangement, a retirement plan holds stock in the C corporation that sponsors it. The mechanics of how that stock got there are covered in our guide to how the ROBS, or qualified employer securities, transaction works. Exiting reverses the position. The plan needs to stop holding company stock, and the value in the plan needs to become something a participant can roll over or receive.
That distinction matters because two things are often confused. Selling the business is not the same as exiting the plan, and closing the company is not the same as terminating the plan. In each case the plan continues to exist, with its own filing and qualification obligations, until it is formally terminated and its assets are distributed.
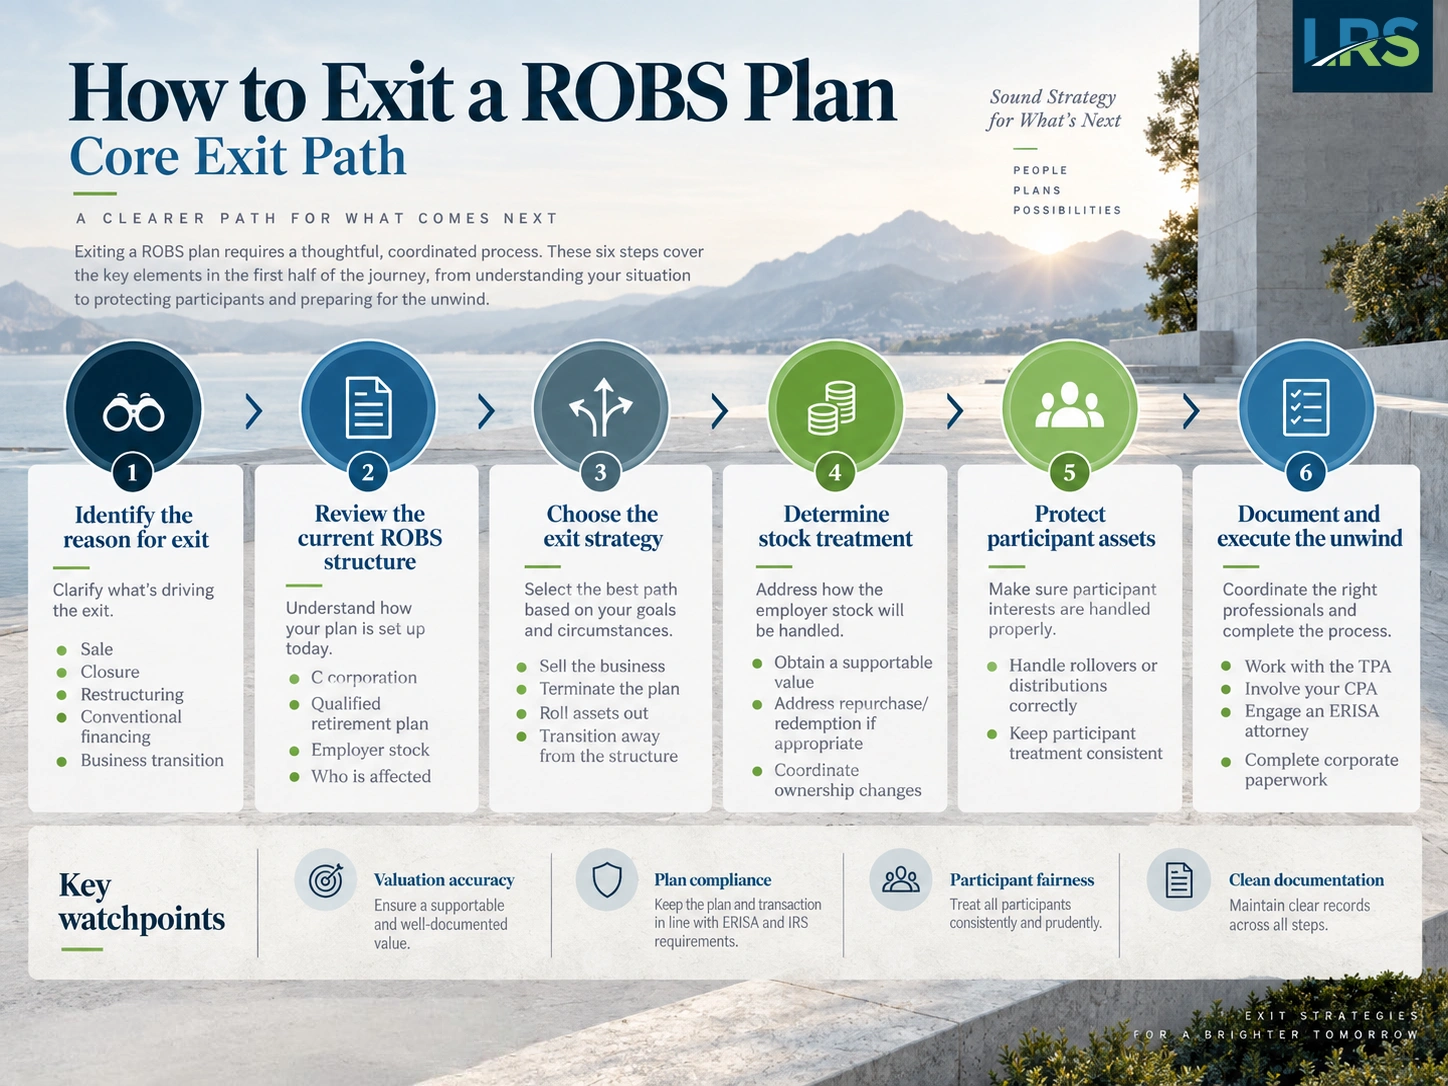
Three things have to happen in some order for a ROBS to unwind: the stock has to be valued, the stock has to leave the plan or be converted to cash, and the plan has to be terminated or converted to a conventional retirement plan. Skipping the first makes the second difficult to document, and doing the third before the second leaves a terminated plan holding an asset it cannot distribute cleanly.
The Four Routes Out
Which route fits depends on whether the business is being sold, continued, or wound down, and on whether the company has cash available.
| Route | What happens to the stock | What it depends on | When it usually fits |
|---|---|---|---|
| Sell the business | A buyer purchases the shares, including those held by the plan | A completed sale, which also establishes the value | The business is being sold as a going concern |
| Corporate redemption | The company buys its own shares back from the plan | Company cash and a supportable valuation | The owner is continuing the business, or funding an RMD |
| In-kind distribution | The shares are distributed to the participant, who holds them personally | A plan document that authorizes it, a valuation, and tax paid from other funds | No company cash is available, or an RMD is due |
| Plan termination | The plan ends once the stock is out or has been valued at what remains | Full vesting, distributions, and the final return | The business is closing, or the plan is no longer needed |
Route one: sell the business
Where a buyer purchases the stock, the plan sells its shares along with any shares held outside the plan and receives cash. The plan then holds cash rather than stock, and the participant can roll that balance to an IRA or another employer plan, or take it as a distribution. This is the cleanest route because the sale price establishes the value, and no separate appraisal question arises for the shares that changed hands.
Where a buyer purchases the assets rather than the stock, the plan still holds shares in a company that now holds sale proceeds instead of a business. That is a different position, and it usually leads to route two or route four.
Route two: the company redeems the stock
The corporation buys its own shares back from the plan, using company cash. The plan receives money, the shares are retired or held as treasury stock, and the participant’s account is then invested like any other 401(k) account. A redemption depends on the company having cash available and on a supportable valuation of the shares being repurchased.
Route three: distribute the stock in kind
Rather than converting the stock to cash inside the plan, the plan distributes the shares themselves to the participant, who then owns them personally. This route needs no company cash, which is often why it is considered. The amount distributed is measured by the value of the shares, and in many cases the distribution may create taxable income for the participant, although the tax consequences depend on the type of distribution and the participant’s circumstances. Withholding, reporting on Form 1099-R and the participant’s ability to pay the tax from other funds all become part of the decision.
Route four: terminate the plan
Termination is the step that ends the plan, and in most exits it follows one of the first three rather than replacing them. Where a business has closed and the stock has no remaining value, termination and the documentation supporting that valuation become the whole exercise. Our plan termination service covers the mechanics, and the requirements are set out below.
A fifth possibility is worth naming because it is not an exit at all. Where the company redeems the stock and the plan continues, the arrangement becomes a conventional 401(k) that happens to have started life as a ROBS. Employees keep their accounts, the plan keeps its history, and the annual obligations continue in the ordinary way through plan administration and recordkeeping.
Why an RMD Can Force a Partial Exit Before You Are Ready
This is the situation that most often brings an owner to the exit question earlier than planned, and it has a specific mechanical problem inside it.
What triggers the requirement
Required minimum distributions under Internal Revenue Code section 401(a)(9) apply to a ROBS plan in the same way they apply to other qualified plans. Once a participant reaches the applicable age, the plan generally has to distribute a minimum amount each year, calculated from the account balance. Our guide to retirement plan deadlines covers the annual timing, and our article on required minimum distributions in a ROBS plan covers the ROBS-specific detail.
The problem the account balance creates
An RMD is a cash-denominated obligation calculated against an account whose main asset is stock in a private company. The plan may hold very little cash, and the stock is not readily marketable. The requirement does not adjust for that, so the plan has to produce a distribution from an asset that does not divide easily.
Two questions follow, and they are the ones people search for most: can the distribution be made in shares rather than cash, and can the company buy shares back to create the cash. Both are generally available, and both depend on the plan document permitting the form of distribution and on a supportable valuation of the shares.
Taking the distribution in kind
An in-kind distribution moves shares out of the plan to the participant rather than cash. The amount distributed is measured by the value of those shares, which is why the valuation question arrives before the distribution question. In many cases, the distribution may create taxable income for the participant, although the tax consequences depend on the type of distribution and the participant’s circumstances. The plan reports the distribution in the ordinary way, and because the participant receives shares rather than money, the tax is typically paid from other funds.
The plan document controls whether this is available at all. The Internal Revenue Manual notes that qualified plans state the forms of distribution in which they will pay participants and beneficiaries, and a plan generally must authorize in-kind distributions before they can be made, which may require review or amendment of plan documents.
Redeeming shares to create the cash
The alternative is for the corporation to buy back enough shares to fund the distribution, leaving the plan with cash to pay the RMD and a smaller shareholding. This keeps the distribution in cash, which is administratively simpler for the participant, and it depends on the company having the money and on the same valuation work.
Where an RMD recurs each year, the practical consequence is that a redemption-based approach unwinds the ROBS position gradually, one distribution at a time, while an in-kind approach moves shares out of the plan in stages. Either way the exit begins earlier than a sale would have started it, which is worth planning for rather than discovering.
Valuation: the Step Every Route Depends On
Every route above turns on the same question, which is what the shares are worth. A sale answers it with a price. A redemption, an in-kind distribution and a termination all have to answer it some other way. Depending on the circumstances, a qualified independent valuation professional may be necessary to support the value used for distributions, redemptions, reporting, or plan termination.
Valuation is also the issue the IRS has been most explicit about. In its 2008 memorandum on these arrangements, the Employee Plans division wrote that an attribute common to the design is the assignment of newly created enterprise stock into a qualified plan, the valuation of which may be questionable. The same concern applies on the way out, where the value determines how much comes out of the plan and how much tax is paid.
A plan also reports the value of its assets on its annual return each year it exists, which our guide to finding and reading a Form 5500 covers, so valuation is not only an exit question. It is the accumulated answer to a question the plan has been asked every year.
Who May Buy the Stock, and Who May Not
This is the constraint that surprises owners most often. The plan holds an asset. The owner would like to buy it. That transaction is not straightforward.
Internal Revenue Code section 4975 prohibits certain transactions between a plan and a disqualified person, a category that includes a fiduciary of the plan, the employer whose employees are covered, and owners above defined thresholds. A sale or exchange of property between the plan and a disqualified person is among the transactions listed. Because the owner of a ROBS company is generally both the fiduciary and a substantial owner, a personal purchase of the shares from the plan raises the question directly.
A corporate redemption is a different transaction from a personal purchase, and exemptions exist for certain acquisitions and sales of qualifying employer securities where conditions are met. The consequences of getting it wrong are set out in our guide to the compliance issues that arise most often in ROBS plans. Whether an exemption applies depends on the specific facts and should be reviewed with qualified legal or tax counsel.
What Plan Termination Involves
Once the stock is out of the plan, or has been determined to have no remaining value, termination is a defined process rather than a decision to stop filing.
- Adopt a formal termination. The sponsor adopts a resolution establishing the termination date and amends the plan document as needed. The Internal Revenue Manual notes that a proposed termination date generally may not be retroactive.
- Vest all affected accounts. The IRS states that when a plan terminates, the accrued benefits of all affected employees must become 100% vested under Internal Revenue Code section 411(d)(3). In a plan with employees beyond the owner, that can change what is payable.
- Value what the plan holds. Distributions are measured by value, so a current valuation of any remaining asset is needed before accounts can be settled.
- Notify participants and process distributions. Participants elect a rollover or a distribution, and the plan pays out. The IRS expects assets to be distributed as soon as administratively feasible, and its guidance describes that as generally within one year of the termination date.
- File the final returns. The plan files a final annual return marked as such. One-participant plans file the Form 5500-EZ, and the IRS has noted that missed 5500-EZ filings were a common finding in its ROBS compliance work.
A determination letter on termination is optional. The IRS accepts Form 5310 from terminating plans and reviews the application, and its own FAQ notes that the review may last several months and that the employer is not required to hold assets while it runs. Whether the additional certainty is worth the time is a judgement that depends on the plan’s history.
A plan that stops operating without completing these steps is not a terminated plan. The IRS position is that a plan which does not distribute assets as soon as administratively feasible is treated as an ongoing plan and has to continue meeting the qualification requirements. That is the position several of the plans in the IRS compliance project were found in, and unwinding it later is more work than doing it in order.
When the Business Did Not Work
Not every exit follows a sale. Where the company has failed, the plan holds stock in a business with little or no value, and the exit is mostly a documentation exercise.
The steps are the same, but the valuation carries more weight, because the plan is reporting that an asset it once valued at the amount rolled in is now worth substantially less or nothing at all. Supporting that with contemporaneous records, financial statements and a defensible valuation is what separates a documented loss from an unexplained one. Where filings were missed along the way, the correction programs described in the IRS 401(k) Plan Fix-It Guide and in our consulting and correction services are generally the route back, and our guide to what an IRS or DOL notice means covers what to do if one has already arrived.
The loss itself falls inside the retirement plan rather than on the individual’s tax return, which is a consequence of the structure that owners are not always expecting. How that interacts with an individual’s overall position is a question for a tax advisor on the specific facts.
What the Plan Has to Do Every Year While It Holds Stock
An exit is easier or harder depending on how the plan was run before it started. Three annual obligations do most of the work of keeping an exit straightforward, and each one is also a place the IRS looks.
An annual valuation
A plan reports the value of its assets each year, and where the asset is stock in a private company, that value has to come from somewhere. A plan with a run of contemporaneous valuations arrives at an exit with a documented history. A plan that has carried the same figure since the rollover arrives with a number and no support for it.
The annual return, and which one
Plans holding employer securities are generally barred from the short Form 5500-SF and file the full Form 5500 instead, whatever their size. That is why many small ROBS plans file the full return rather than the 5500-SF or the one-participant 5500-EZ, and why a small ROBS plan’s filing is usually part of the public record. Our guide to finding and reading a Form 5500 covers what those filings show.
The fidelity bond
Persons who handle plan funds are required to be bonded under ERISA section 412, and the maximum bond amount the Department of Labor can require is higher for a plan that holds employer securities. A ROBS plan therefore sits in the higher category by design, which our guide to ERISA fidelity bonds covers in detail.
The IRS compliance project began by looking for sponsors that had received a determination letter and then filed nothing. Annual valuation, the correct annual return and the bond are not exit steps. They are the record an exit is built on, and their absence is what turns a straightforward unwind into a correction project.
If the Company Has Employees
Much of what is written about these arrangements assumes a single owner. Where the business has grown, the exit changes shape.
Employees who satisfied the plan’s eligibility conditions are participants with their own accounts, and those accounts have to be handled alongside the owner’s. On termination, the IRS position is that accrued benefits of all affected employees become fully vested, so an exit can accelerate vesting that a departing employee would not otherwise have reached.
There is also a design question the IRS has raised directly. Its 2008 memorandum notes that these cases should be developed for discrimination issues where a plan covers both highly compensated and non-highly compensated employees and the stock investment option was not extended to everyone. Whether employees were offered the same investment option as the owner is therefore a question an exit can surface, and it is better answered before the plan is being wound down than during.
Partial Exits and What Happens to the Company
Not every exit happens at once. A redemption can take a portion of the shares, leaving the plan holding a smaller stake, which is what a recurring annual distribution requirement tends to produce over time.
On the corporate side, shares repurchased by the company are generally retired or held as treasury stock, and the ownership percentages of everyone else move accordingly. Where the plan held a controlling stake, a redemption shifts control back toward the individual shareholders, which has consequences beyond the plan and belongs in the conversation with the company’s counsel and accountant rather than with the plan’s administrator alone.
A ROBS company is generally a C corporation, because the structure depends on the plan holding stock the corporation issued. Where an owner is considering a change of entity type after the plan no longer holds shares, that is a corporate tax question with its own timing, and it is one of the reasons the order of an exit matters.
What the IRS Looks At
The IRS has published its own view of these arrangements, which makes it possible to be specific rather than speculative about what draws attention.
Employee Plans opened a ROBS compliance project in 2009 to identify traits of compliant and noncompliant arrangements. Its published summary describes focusing initially on companies that sponsored a plan and received a determination letter but did not file a Form 5500 or Form 5500-EZ, and it notes that a determination letter does not protect a sponsor from operating the plan incorrectly or in a discriminatory manner.
Three themes run through that material and through the 2008 memorandum: whether the stock was valued supportably, whether the plan was operated for the benefit of one individual rather than all eligible employees, and whether the required annual filings were made. Each of those is easier to answer at exit if it was answered each year, which is the argument for treating a ROBS as an ongoing plan with ongoing obligations rather than a financing event. Our summary of what an audit of these plans most often finds covers the operational side.
Getting the Order Right
Most of the difficulty in a ROBS exit comes from sequence rather than from any single step.
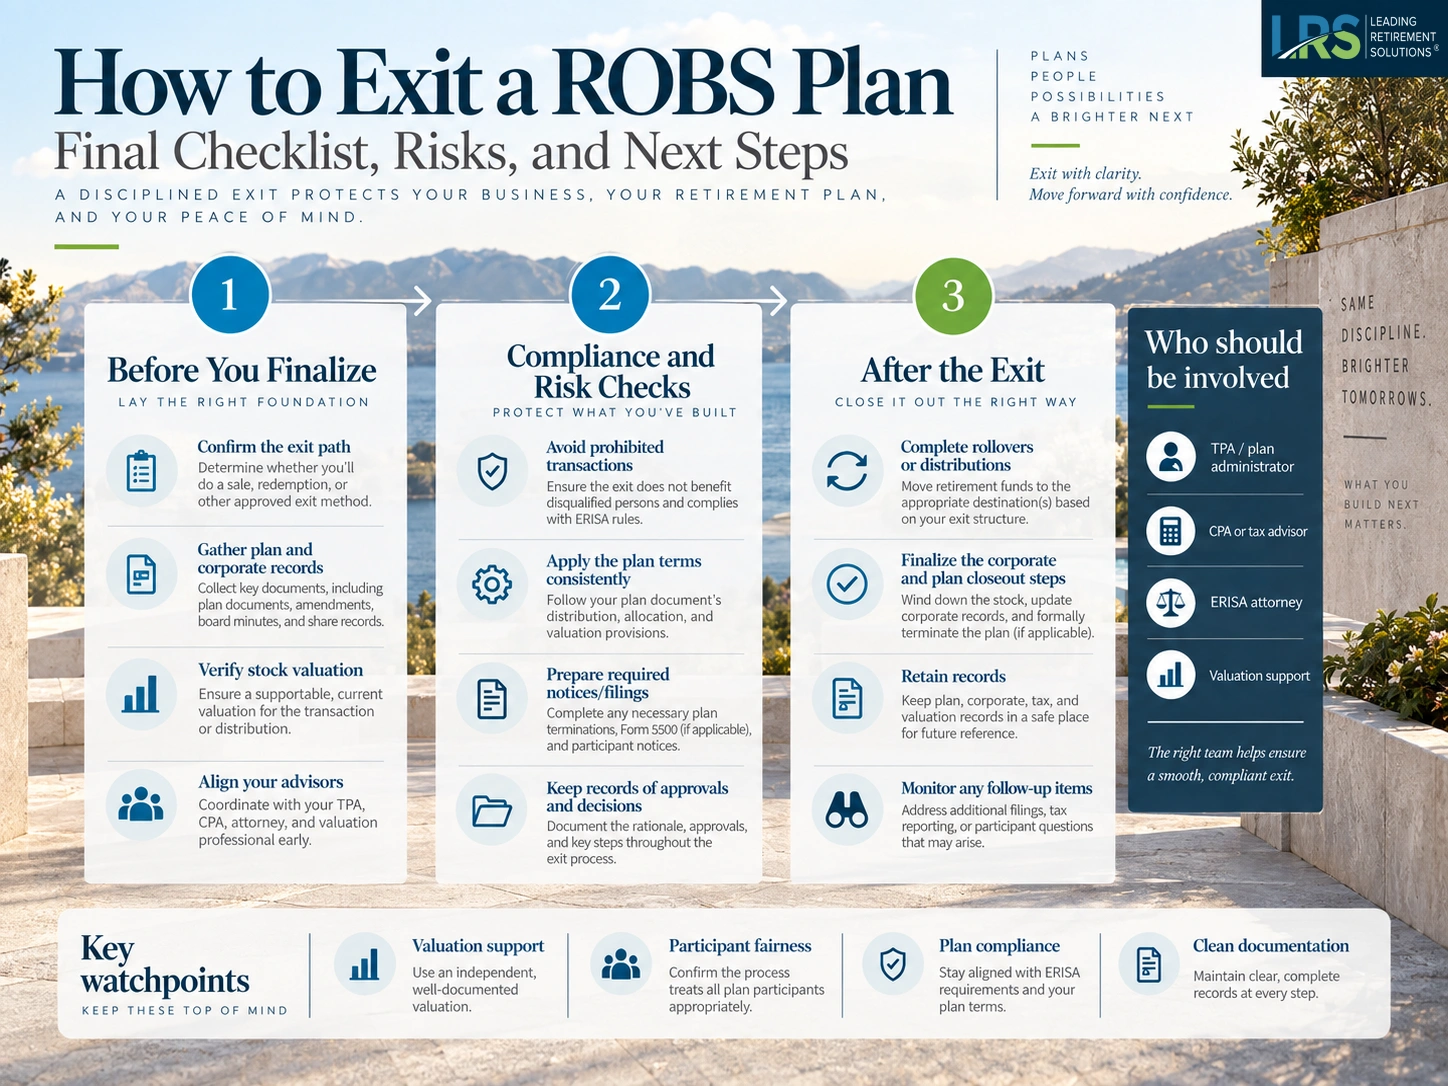
- Decide what is happening to the business first. Sale, continuation or wind-down determines which of the four routes is even available, and the answer changes the rest of the sequence.
- Get the valuation current. Redemption price, distribution amount and final account balances all measure against it, and it is the item most likely to take outside time.
- Confirm what the plan document permits. Whether the plan can distribute in kind, and on what terms, is a document question that may require review or amendment of the plan document before anything else can proceed.
- Move the stock before terminating the plan. A terminated plan still holding shares is harder to settle than an ongoing plan that is selling or redeeming them.
- Complete the filings. The final return, and any missed prior returns, close the plan’s record. Leaving them open leaves the plan open.
Employers who are restructuring rather than exiting entirely may find our guide to retirement plan continuity when restructuring a business covers the intermediate cases.
Common Questions About Exiting a ROBS Plan
How do you exit a ROBS plan?
By removing the employer stock from the plan and then distributing or rolling over what remains. The four common routes are selling the business, having the company redeem the stock from the plan, distributing the stock in kind to the participant, and terminating the plan once the stock has been dealt with. Each depends on a current valuation of the shares.
Can a ROBS plan take a required minimum distribution in company stock?
Generally yes, where the plan document provides for distributions in kind. The shares move to the participant rather than cash, and the amount distributed is measured by the value of those shares. In many cases the distribution may create taxable income for the participant, although the tax consequences depend on the type of distribution and the participant’s circumstances. Because no cash changes hands, the tax is typically paid from other funds. A plan generally must authorize in-kind distributions before they can be made, which may require review or amendment of plan documents.
Can the company buy back stock from the plan to fund an RMD?
A corporate redemption is one of the common ways to create the cash a distribution requires. The company purchases shares from the plan, the plan uses the proceeds to make the distribution, and the plan’s shareholding is reduced. It depends on the company having the funds available and on a supportable valuation of the shares being repurchased.
How is the stock valued when exiting a ROBS?
Where the business is sold, the sale price generally establishes the value. Where it is not, the value has to be determined some other way, and the IRS has said the valuation of stock in these arrangements may be questionable, which is why supportable, contemporaneous valuation work matters more here than in a plan holding marketable securities. Depending on the circumstances, a qualified independent valuation professional may be necessary to support the value used.
Can the business owner buy the stock from the plan personally?
That transaction raises the prohibited transaction rules in Internal Revenue Code section 4975, because a sale or exchange of property between a plan and a disqualified person is among the transactions listed, and the owner of a ROBS company is generally both a fiduciary and a substantial owner. A corporate redemption is a different transaction. Whether an exemption applies depends on the specific facts and should be reviewed with qualified legal or tax counsel.
What happens to a ROBS plan if the business closes?
The plan continues to exist until it is formally terminated. Where the stock has little or no remaining value, the exit becomes largely a valuation and documentation exercise: establish and support the value, vest affected accounts, distribute what remains, and file the final return. A plan that simply stops operating is treated as ongoing and continues to carry qualification and filing obligations.
How long does it take to terminate a ROBS plan?
The IRS expects assets to be distributed as soon as administratively feasible after the termination date, and describes that as generally within one year. The practical timeline depends on how quickly the valuation, any redemption or sale, and the participant elections can be completed.
Do you have to file a Form 5500 for a ROBS plan?
Yes, in the ordinary way. One-participant plans file the Form 5500-EZ once combined plan assets pass the filing threshold, and a final return is filed for the year the plan terminates. Missed filings were a common finding in the IRS compliance work on these arrangements, and unfiled returns are usually resolvable through the available correction programs.
Is exiting a ROBS a taxable event?
It depends on the route. A rollover of plan proceeds to an IRA or another employer plan is generally not taxable. A distribution to the participant, whether in cash or in shares, may create taxable income, although the tax consequences depend on the type of distribution and the participant’s circumstances. The corporate side of a sale or redemption has its own treatment, which is a question for the company’s tax advisor on the specific facts.
Does the plan have to be terminated after the stock is sold?
No. Where the stock leaves the plan and the plan continues, it operates as a conventional 401(k) from that point, with the same annual obligations as any other plan. Termination is a separate decision, and it is the right one where the business itself is ending or the plan is no longer wanted.
What does the IRS look at in a ROBS plan?
Its published material points at three areas: whether the stock was valued supportably, whether the plan benefited one individual rather than all eligible employees, and whether the required annual returns were filed. Its compliance project began with sponsors that had a determination letter but no filings, and the IRS has said a determination letter does not protect a sponsor that operates the plan incorrectly.
Can a ROBS plan be converted into a regular 401(k)?
Once the plan no longer holds employer stock, it operates as a conventional 401(k). The plan document, the service arrangements and the annual work continue in the ordinary way. For employers who want to keep the plan running after the stock is out, that is often the simplest outcome.
Does a ROBS plan file a Form 5500 or a Form 5500-EZ?
Plans holding employer securities are generally barred from the short Form 5500-SF, and many ROBS plans also fall outside the one-participant definition because the plan rather than the individual owns the business. The result is that small ROBS plans often file the full Form 5500, which is part of the public record.
What happens to employees’ accounts when a ROBS plan terminates?
They are handled alongside the owner’s. The IRS states that on termination the accrued benefits of all affected employees become fully vested, so a termination can accelerate vesting an employee would not otherwise have reached, and each participant elects a rollover or a distribution in the ordinary way.
Can the plan sell only part of its shares?
Yes. A redemption can take a portion of the shares, leaving the plan with cash and a smaller shareholding. Where a distribution requirement recurs annually, that is often what happens in practice, and the position unwinds over several years rather than in one transaction.
Where to Start
The first question in any ROBS exit is not which route to take. It is what the shares are worth and what the plan document permits, because those two answers determine which routes are open.
Leading Retirement Solutions administers ROBS plans and works with business owners through sales, redemptions, distributions and terminations, including plans that arrive with filings outstanding.
Sources and Review
Every regulatory statement in this guide traces to a primary federal source. No promoter, competitor, vendor or aggregator is cited or linked anywhere, which matters more on this topic than most, because much of the commercial material written about these arrangements comes from firms selling them. Each link opens the current version of the page on the issuing body’s own site.
- Internal Revenue ServiceRollovers as business start-ups compliance projectThe project’s scope, the determination letter point, and the Form 5500 filing finding.
- Internal Revenue ServiceGuidelines regarding rollovers as business start-ups, 1 October 2008The valuation concern and the discrimination point, in the IRS’s own words.
- Internal Revenue ServiceInternal Revenue Manual 7.12.1, Plan terminationsForms of distribution stated in the plan document, termination dates, and Form 5310.
- Internal Revenue ServiceRetirement plans FAQs regarding plan terminationsFull vesting on termination, distribution as soon as administratively feasible, and the ongoing plan position.
- U.S. House of Representatives26 U.S. Code 4975, Tax on prohibited transactionsProhibited transactions and the definition of a disqualified person.
- U.S. House of Representatives26 U.S. Code 401, Qualified pension, profit-sharing and stock bonus plansThe required minimum distribution rules at section 401(a)(9).
- Internal Revenue ServiceOne-participant 401(k) plansForm 5500-EZ filing obligations and the threshold that triggers them.
- Internal Revenue Service401(k) plan Fix-It GuideCorrection of operational failures, including missed filings and testing errors.
- Internal Revenue ServiceAbout Form 5310, Application for Determination for Terminating PlanThe optional determination letter on termination.
- U.S. Department of LaborEFAST2 filing systemWhere filed annual returns become part of the public record.
Leading Retirement Solutions is a third-party administrator serving employers in all 50 states. Provided for general information only and not legal or tax advice. Valuation, tax treatment, vesting, filing obligations and the routes available on exit depend on your plan document and the specific facts of your plan. Confirm requirements with your advisors or the applicable agency before acting.
Talk to us about exiting a ROBS plan
Leading Retirement Solutions provides plan design, administration, recordkeeping and correction support for employers across the country.