Plan Sponsor Guide · Updated October 2026
A defined benefit plan is an employer retirement plan that promises each participant a specified benefit at retirement, usually a monthly amount set by a formula based on pay and years of service. The employer funds the plan, an actuary calculates the contributions each year, and many private sector plans are covered by Pension Benefit Guaranty Corporation insurance.1, 2,12
A cash balance plan is a type of defined benefit plan that expresses the promised benefit as an account balance instead of a monthly amount. This guide covers how both work, from how the benefit is set to how a plan ends. For how defined benefit plans compare with 401(k) and other defined contribution plans, see our guide to defined benefit versus defined contribution plans.
- A defined benefit plan promises a benefit, not an account. The plan’s formula generally determines what each participant receives, and the employer is generally responsible for funding it.
- An enrolled actuary generally determines the minimum required contribution each year and reports the plan’s funding information on Schedule SB of the Form 5500.
- Many private sector defined benefit plans, including many cash balance plans, are covered by PBGC insurance. Coverage depends on plan type, employer status, and other factors under ERISA.
- A cash balance plan credits each participant with pay credits and interest credits to a hypothetical account. The plan’s assets are pooled and invested by the plan, not by participants.
- Ending a defined benefit plan is a formal process. A plan covered by the PBGC generally needs enough assets to pay all benefit liabilities before it can close in a standard termination.
What a Defined Benefit Plan Is
A defined benefit plan promises a specific benefit at retirement rather than a contribution today. The IRS describes the promised benefit as either an exact dollar amount or, more commonly, an amount calculated by a plan formula that considers factors such as salary and service.1 The Department of Labor describes these plans as providing a fixed, pre-established benefit for employees at retirement.2
ERISA defines the term by exclusion. Any pension plan that is not an individual account plan is a defined benefit plan.3 That is why a cash balance plan, which looks like an account to the participant, is still a defined benefit plan in law: the account is a measure of the promise, not a separate pot of assets belonging to the participant.
Most employers can sponsor a defined benefit plan, including many self-employed individuals. The IRS describes defined benefit plans among the qualified plans available to small businesses and the self-employed.25 A small employer starting a new qualified plan may also qualify for a tax credit toward the startup costs.26
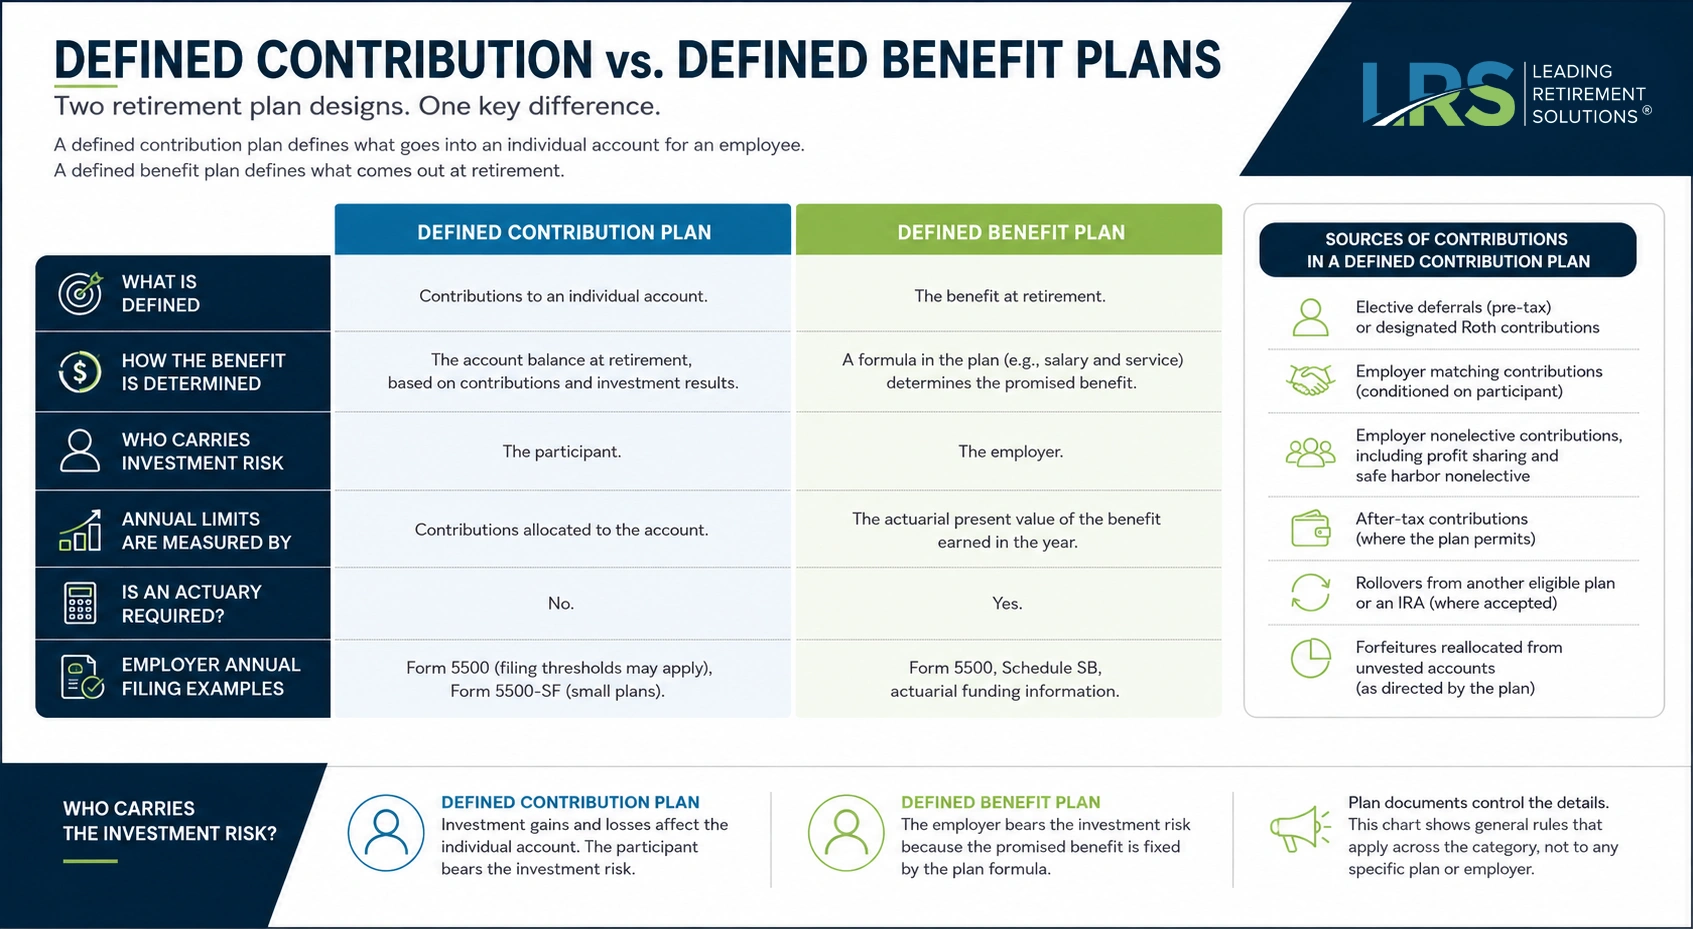
Because the benefit is promised, the plan’s assets are generally held in a single trust and invested together. Participants generally do not choose investments, and the benefit a participant receives does not rise or fall with the plan’s investment results.2,15 How that difference plays out against a 401(k) is covered in our comparison guide.
How the Benefit Is Set
The benefit formula in the plan document is the starting point for everything else. It generally shapes what each participant has earned, which in turn shapes what the plan needs to hold and what the employer contributes.
Most traditional formulas multiply three things together: a percentage set by the plan, the participant’s years of service, and a measure of pay. The measure of pay may be an average of the participant’s highest or final years, or an average across the whole career.1
The figures below are hypothetical and are shown only to explain how a formula operates. A plan’s own formula is set in its document.
Suppose a plan provides 1.5 percent of final average pay for each year of service. A participant who retires at the plan’s normal retirement age with 20 years of service would receive an annual benefit of 30 percent of their final average pay (1.5 percent multiplied by 20 years), generally paid monthly for life.
Several rules in the Internal Revenue Code shape how that formula works in practice.
- Normal retirement age. The plan defines it, and it generally cannot be later than age 65 or the fifth anniversary of the participant’s entry into the plan, whichever is later.4
- Vesting. A participant’s accrued benefit funded by employer contributions generally vests under either a five-year cliff schedule or a three-to-seven-year graded schedule, unless the plan provides faster vesting. Cash balance plans follow a shorter schedule, covered below.4
- The annual benefit limit. Section 415(b) caps the annual benefit a defined benefit plan can pay. The dollar limit is adjusted each year and published in the IRS cost-of-living table, and our 2026 contribution maximums guide lists the current figures.5,6
Types of Defined Benefit Plans
Defined benefit plans differ mainly in how they measure the benefit. The table describes the designs most often seen, as the governing statutes and agency guidance describe them.
| Design | How the benefit is measured | Source |
|---|---|---|
| Final average pay | A percentage of the participant’s average pay over a set number of final or highest-paid years, multiplied by years of service | IRS1 |
| Career average pay | A percentage of pay earned in each year of participation, accumulated across the whole career | IRS1 |
| Flat benefit | A stated dollar amount, either fixed or multiplied by years of service | IRS1 |
| Cash balance | A hypothetical account balance built from pay credits and interest credits | DOL15 |
| Pension equity | A lump-sum amount expressed as an accumulated percentage of final average pay | 26 U.S.C. §411(a)(13)4 |
| Multiemployer | Any of the above, maintained under collective bargaining agreements with more than one employer | ERISA §3(37)3 |
How a particular plan measures its benefit is set by its plan document. Some plans combine features of more than one design.
Cash balance and pension equity plans are sometimes called hybrid plans, because they are defined benefit plans that express the benefit in a way that resembles an account. The Code groups them together as plans that use a lump-sum based benefit formula.4
Funding and the Role of the Actuary
Each year, an enrolled actuary generally determines the minimum contribution the employer is required to make to a single-employer defined benefit plan. That calculation follows section 430 of the Code.7
In general terms, the minimum required contribution covers the cost of benefits participants earn during the year, known as the target normal cost. If the plan’s assets fall short of its funding target, it also includes a charge that spreads the shortfall over a period of years set by statute.7 The calculation uses interest rates, mortality tables, and methods that the Code and IRS guidance prescribe, which is why the result can change from one year to the next even when the plan itself has not.
- Timing. The minimum required contribution is generally due eight and a half months after the end of the plan year. A plan that had a funding shortfall in the prior year generally has to make quarterly installments during the year as well.7
- Deductible contributions. In some cases, tax rules may permit deductible contributions above the minimum required contribution. The amount depends on the plan’s circumstances and applicable tax rules.8
- Missing the minimum. A failure to meet the minimum funding standard can result in an excise tax on the employer.9
Schedule SB and Annual Reporting
A defined benefit plan files a Form 5500 each year, and a single-employer defined benefit plan generally attaches Schedule SB, the actuarial information schedule. Multiemployer plans attach Schedule MB instead. The schedule is signed by the plan’s enrolled actuary.10
Schedule SB reports the plan’s funding target, the value of its assets, the actuarial assumptions used, and the minimum required contribution. It is the public record of the actuary’s work for the year.10
- Plan size. For defined benefit plans, participant counts used for Form 5500 filing purposes are determined under applicable Department of Labor reporting rules and may include active employees, retirees, and former employees with vested benefits. A plan that files as a large plan generally requires an independent audit. LRS assists plan sponsors with audit preparation and coordination as part of our large plan audit support services.10
- One-participant plans. One-participant plans are subject to separate filing requirements, generally on Form 5500-EZ rather than Form 5500. Those requirements, including related actuarial reporting, are set out in the current IRS instructions for Form 5500-EZ.11
For what Form 5500 is, its deadlines, and how to look up a filing, see our guide to searching Form 5500 filings.
PBGC Coverage and Premiums
The Pension Benefit Guaranty Corporation is a federal agency that insures benefits under many private sector defined benefit plans, including many cash balance plans.13,16 If a covered plan ends without enough money to pay its benefits, the PBGC generally pays benefits up to limits set by law.
Coverage is set by Title IV of ERISA, and certain plans are excluded from PBGC coverage. Coverage depends on the type of employer, plan structure, and participant population.12
A covered plan generally pays annual premiums to the PBGC. There is a flat-rate premium for each participant and a variable-rate premium tied to the plan’s unfunded vested benefits. Rates are adjusted each year and published on the PBGC’s premium filing page.14
Cash Balance Plans
A cash balance plan is a defined benefit plan that defines each participant’s benefit as a stated account balance. The Department of Labor describes it as a plan in which each participant’s account is credited each year with a pay credit and an interest credit.15
How the account grows
| Component | What it is | Source |
|---|---|---|
| Pay credit | An amount added each year, such as a percentage of the participant’s compensation or a flat dollar amount | DOL15 |
| Interest credit | A return added to the balance at either a fixed rate or a variable rate tied to an index | DOL15 |
| Interest credit limit | The rate generally cannot exceed a market rate of return, as defined in Treasury regulations | 26 CFR §1.411(b)(5)-117 |
| Plan assets | Pooled in the plan trust and invested by the plan, so investment gains and losses do not change the participant’s credited balance | DOL15,16 |
The plan document sets both credits. The account is a hypothetical record of the benefit, not a separate holding of plan assets.
Because the balance grows by credits rather than by investment returns, the employer’s required contribution still depends on how the plan’s actual assets perform against the promised credits. That is why a cash balance plan carries the same actuarial funding and Schedule SB requirements as any other defined benefit plan.7,10
Vesting and age rules
Cash balance plans are generally subject to accelerated vesting requirements, and many provide full vesting after three years of service, subject to applicable law and plan terms.4 The Code also sets a specific test for whether a cash balance formula is age discriminatory, and the Treasury regulations explain how that test and the interest credit limit apply.4,17
How benefits are paid
Like other defined benefit plans, a cash balance plan generally must offer payment as a lifetime annuity. For a married participant, the default form is generally a qualified joint and survivor annuity, and choosing a different form generally requires the spouse’s written consent.16,18 Many cash balance plans also offer a lump sum equal to the account balance, which can generally be rolled over to an IRA or another employer plan. Whether a lump sum is available depends on the plan document.15
Plan loans are generally permitted only if the plan document provides for them. The IRS notes that a plan may, but is not required to, offer loans, so whether a particular cash balance plan permits them depends on its terms.19
Benefits are paid when permitted under the plan document and applicable law, such as upon separation from service, retirement, disability, death, or plan termination. Access to benefits before those events is limited and depends on the plan’s terms and legal requirements.4,15
Sponsoring a Cash Balance Plan Alongside a 401(k)
Employers that sponsor a cash balance plan often sponsor a 401(k) plan as well, and the two are administered as separate plans with separate documents, trusts, and Form 5500 filings.10 The rules below describe how they interact. Whether sponsoring both suits an employer is a separate question, covered in our comparison guide.
- Nondiscrimination testing. The two plans can be tested together for nondiscrimination, which Treasury regulations permit on a benefits basis. How the plans are tested depends on their designs and the employer’s workforce.20
- Minimum participation. Qualified defined benefit plans are generally subject to minimum participation requirements under federal tax law. How those requirements apply depends on workforce size and plan design.21
- Combined deduction limit. Tax rules may limit deductible contributions when an employer sponsors both a defined benefit plan and a defined contribution plan for the same workforce. The calculation can vary based on plan design and other factors under the Internal Revenue Code. Employers typically review these limits with their actuary and tax advisor.8
Each of these rules depends on the plans’ documents and on the facts for the year, which is why combined designs are reviewed by the plan’s administrator and actuary together.
Ending a Defined Benefit Plan
An employer can end a defined benefit plan, but the process is formal and governed by both the IRS and, for a covered plan, the PBGC. When a plan terminates, affected participants generally become fully vested in their accrued benefits.24
A plan covered by the PBGC can generally close in a standard termination only if its assets are sufficient to pay all benefit liabilities. A plan that cannot meet that test may generally close only through a distress termination, which has its own conditions, or through action by the PBGC.22,23
| Stage | What happens | Source |
|---|---|---|
| Notice of intent | Participants and other affected parties are notified of the proposed termination date, within a window set by statute | ERISA §404122 |
| Filing with the PBGC | The plan administrator files a standard termination notice, and participants receive a notice of their plan benefits | PBGC23 |
| Distribution | Benefits are paid out as lump sums or through annuities purchased from an insurer, under the plan’s terms | ERISA §404122 |
| Certification | The administrator certifies to the PBGC that all benefits have been distributed | PBGC23 |
| Final reporting | A final Form 5500 is filed, and the employer may ask the IRS for a determination letter on the termination | IRS24 |
A general outline of a standard termination for a PBGC-covered plan. Notice periods and filings are set by statute and PBGC rules. A plan not covered by the PBGC does not make the PBGC filings.
Our plan termination services help plan sponsors coordinate the required notices, filings, and benefit distributions throughout the termination process.
Frequently Asked Questions
What is a defined benefit plan?
An employer retirement plan that promises each participant a specified benefit at retirement, usually a monthly amount based on pay and years of service. The employer generally funds the plan, an enrolled actuary calculates the required contributions, and many private sector plans are covered by PBGC insurance.
How does a defined benefit plan work?
The plan document sets a benefit formula. Each year an actuary generally measures the benefits participants have earned, compares them with the plan’s assets, and determines the minimum required contribution. The assets are invested together in a trust, and benefits are paid from that trust at retirement.
What is a cash balance plan?
A defined benefit plan that expresses each participant’s benefit as an account balance. The balance grows by a yearly pay credit and an interest credit set by the plan, while the plan’s actual assets are pooled and invested by the plan.
Is a cash balance plan considered a 401(k)?
No. A cash balance plan is a defined benefit plan, so the employer generally funds it, an actuary determines the required contributions, it generally reports on Schedule SB, and it is often covered by PBGC insurance. A 401(k) is a defined contribution plan in which the account reflects actual contributions and investment results. Employers can sponsor both.
How is a cash balance plan paid out?
It generally must offer a lifetime annuity, and for a married participant the default is generally a joint and survivor annuity unless the spouse consents to another form. Many plans also offer a lump sum equal to the account balance, which can generally be rolled over. The options available depend on the plan document.
Can you borrow from a cash balance plan?
Only if the plan document provides for loans. A qualified plan may offer loans but is not required to, so the answer depends on the terms of the particular plan.
Can I withdraw from a cash balance plan?
Benefits are paid when permitted under the plan document and applicable law, such as upon separation from service, retirement, disability, death, or plan termination. Access to benefits before those events is limited and depends on the plan’s terms and legal requirements.
Are defined benefit plans insured by the PBGC?
Many private sector defined benefit plans, including many cash balance plans, are covered by PBGC insurance. Certain plans are excluded under ERISA, and coverage depends on the type of employer, plan structure, and participant population. A covered plan generally pays annual premiums.
What does sponsoring a defined benefit plan involve?
Generally, an annual actuarial valuation, a minimum required contribution that can vary from year to year, a Form 5500 with Schedule SB, PBGC premiums for a covered plan, and a formal termination process if the plan ends. These obligations generally continue for as long as the plan has benefits to pay.
Can a self-employed person have a defined benefit plan?
In many cases, yes. The IRS describes defined benefit plans among the qualified plans available to self-employed individuals and small businesses. A plan covering only an owner, or an owner and spouse, is subject to separate filing requirements, generally on Form 5500-EZ. A small employer starting a new plan may also qualify for a tax credit for startup costs.
What happens when a defined benefit plan is terminated?
Affected participants generally become fully vested. A PBGC-covered plan generally needs enough assets to pay all benefit liabilities to close in a standard termination, followed by notices, filings, distribution of benefits, and a final Form 5500.
Related Reading
- Defined benefit versus defined contribution plans, on how the two plan types compare and how employers weigh them.
- 2026 IRS contribution maximums, including the current defined benefit limit.
- Searching Form 5500 filings by company name, on the annual report most plans file.
- State-approved qualifying retirement plans, on which arrangements satisfy the state mandates.
- Starting a new retirement plan with Leading Retirement Solutions.
Sources
Every substantive statement above is drawn from the following primary sources. Numbers in the text refer to this list. Links were verified at the time of writing.
- Internal Revenue ServiceDefined benefit plan
- U.S. Department of LaborTypes of retirement plans
- U.S. Code29 U.S.C. §1002, Definitions (ERISA §3)Cited for the defined benefit plan definition in §3(35) and multiemployer plans in §3(37).
- U.S. Code26 U.S.C. §411, Minimum vesting standardsCited for normal retirement age, vesting schedules, applicable defined benefit plans, and the cash balance age test.
- U.S. Code26 U.S.C. §415, Limitations on benefits and contribution under qualified plans
- Internal Revenue ServiceCOLA increases for dollar limitations on benefits and contributions
- U.S. Code26 U.S.C. §430, Minimum funding standards for single-employer defined benefit pension plans
- U.S. Code26 U.S.C. §404, Deduction for contributions of an employer to an employees’ trustCited for the deduction range and the combined plan limit.
- U.S. Code26 U.S.C. §4971, Taxes on failure to meet minimum funding standards
- U.S. Department of LaborInstructions for Form 5500Cited for Schedules SB and MB, the actuary’s signature, participant counting, and the audit requirement.
- Internal Revenue ServiceAbout Form 5500-EZ, Annual Return of a One-Participant (Owners/Partners and Their Spouses) Retirement Plan or a Foreign Plan
- U.S. Code29 U.S.C. §1321, Coverage (ERISA §4021)
- Pension Benefit Guaranty CorporationWho we are
- Pension Benefit Guaranty CorporationPremium filings
- U.S. Department of LaborFact sheet: Cash balance pension plans
- U.S. Department of LaborFAQs about cash balance pension plans
- Code of Federal Regulations26 CFR §1.411(b)(5)-1, Reduction in rate of benefit accrual under a defined benefit planCited for the market rate of return limit.
- U.S. Code26 U.S.C. §417, Definitions and special rules for purposes of minimum survivor annuity requirements
- Internal Revenue ServiceRetirement plans FAQs regarding loans
- Code of Federal Regulations26 CFR §1.401(a)(4)-8, Cross-testing
- U.S. Code26 U.S.C. §401, Qualified pension, profit-sharing, and stock bonus plansCited for the minimum participation rule in §401(a)(26).
- U.S. Code29 U.S.C. §1341, Termination of single-employer plans (ERISA §4041)
- Pension Benefit Guaranty CorporationPlan terminations
- Internal Revenue ServiceRetirement plans FAQs regarding plan terminations
- Internal Revenue ServicePublication 560, Retirement Plans for Small Business (SEP, SIMPLE, and Qualified Plans)
- Internal Revenue ServiceInstructions for Form 8881, Credit for Small Employer Pension Plan Startup Costs, Auto-Enrollment, and Military Spouse Participation
About Leading Retirement Solutions. Leading Retirement Solutions is a Seattle-based third-party administrator that has designed, administered, and corrected retirement plans for employers across the country since 2017, including the Leading Cannabis 401(k)®. Defined benefit and cash balance plan administration, Form 5500 preparation, and plan terminations are part of the work we do.
Provided for general information only and not legal, tax, or investment advice. How a plan’s benefits, funding, coverage, and termination work depends on that plan’s documents and circumstances.