Updated
Can a cannabis business deduct its business expenses?
It depends on what the business sells, and since April 2026 the answer has split in two. Section 280E of the Internal Revenue Code disallows any deduction or credit for amounts paid or incurred in a trade or business that consists of trafficking in a Schedule I or Schedule II controlled substance. The IRS has stated that this applies to businesses that sell marijuana even in states where the sale is legal, and that 280E does not prevent a business from reducing its gross receipts by properly calculated cost of goods sold (IR-2024-177, June 28, 2024).
A Justice Department final order effective April 28, 2026 then moved two categories of marijuana to Schedule III: marijuana in FDA-approved drug products, and marijuana subject to a state medical marijuana license. Adult-use marijuana, bulk marijuana and unlicensed crops remain in Schedule I, according to the Treasury Department’s April 23, 2026 announcement. Treasury and the IRS said in the same announcement that rescheduling generally removes 280E as a bar to deductions and credits for businesses that, as a result of the order, no longer traffic in Schedule I or II substances, and that formal guidance would follow.
| Type of business | Schedule after April 28, 2026 | Where 280E stands |
|---|---|---|
| Adult-use (recreational) plant-touching business | Schedule I | 280E applies. Gross receipts reduced by cost of goods sold; other deductions and credits disallowed. |
| Business operating under a state medical marijuana license | Schedule III | Treasury has announced that rescheduling is expected to generally remove 280E as a barrier for qualifying activity, subject to future IRS and Treasury guidance. |
| Business with both medical and adult-use activity | Both | Treasury expects guidance on applying 280E only to the Schedule I or II activity, for example by apportioning expenses. |
| Business that does not sell or produce marijuana (for example, a software or equipment supplier) | Not applicable | 280E’s text reaches businesses consisting of trafficking in Schedule I or II substances. Whether a given business falls inside it depends on its facts. |
Sources: 26 U.S.C. 280E; U.S. Treasury, April 23, 2026; U.S. Department of Justice.
Key dates in the 280E story
- 1982Section 280E enacted (Pub. L. 97‑248), denying deductions and credits to businesses trafficking in Schedule I or II substances.
- 2007CHAMP, U.S. Tax Court. A substantial caregiving business was treated as a trade or business separate from the organization’s medical marijuana activity.
- 2015Olive, Ninth Circuit, and Chief Counsel Memorandum 201504011. Free amenities do not create a second business; cost of goods sold follows the pre-1986 inventory rules.
- 2021Patients Mutual (Harborside), Ninth Circuit. A reselling dispensary limited to the purchased-goods inventory rule.
- June 2024IR-2024-177. The IRS states 280E still applies and refund claims are not valid while marijuana stays in Schedule I.
- Dec 2025Executive Order directs the Attorney General to complete moving medical marijuana to Schedule III.
- Apr 28, 2026Final order effective. State-licensed medical marijuana moves to Schedule III; adult-use stays in Schedule I. Treasury announces guidance on April 23.
- June 29, 2026DEA hearing begins on moving marijuana more broadly to Schedule III.
Sources: 26 U.S.C. 280E and notes; Olive v. Commissioner, 9th Cir. 2015; CCA 201504011; Patients Mutual v. Commissioner, 9th Cir. 2021; IR-2024-177; U.S. Treasury; 91 FR 22777.
What 280E still allows: cost of goods sold
Section 280E disallows deductions and credits, but cost of goods sold is not a deduction. It is subtracted from gross receipts to reach gross income, which is why the IRS confirms that a business subject to 280E can still reduce its receipts by properly calculated cost of goods sold.
How that cost is calculated is where most of the disputes arise. In Chief Counsel Memorandum 201504011 (2015), the IRS set out its position that a business trafficking in a Schedule I or II substance determines cost of goods sold under the section 471 inventory-costing regulations as they existed when 280E was enacted in 1982, rather than under the broader uniform capitalization rules of section 263A added in 1986. The memorandum draws a distinction that matters in practice:
Resellers
Resellers, such as a dispensary buying finished product, were subject to the regulation covering purchased goods, which generally limits inventoriable cost to the purchase price and the costs of acquiring possession of the goods.
Producers
Producers, such as a cultivator or manufacturer, were subject to the full-absorption regulations, which include the direct and indirect costs of production.
The Ninth Circuit applied the reseller rule in 2021 in Patients Mutual Assistance Collective Corp. v. Commissioner, the Harborside dispensary case, holding that a dispensary that buys the marijuana it resells and values inventory at cost must follow the purchased-goods regulation, section 1.471-3(b), and rejecting its argument that other expenditures could be treated as inventory cost instead.
| Business model | Inventory rule under the IRS position | What can count as cost of goods sold |
|---|---|---|
| Reseller (buys finished product, such as a retail dispensary) | Treas. Reg. 1.471-3(b) | Generally the purchase price and the costs of acquiring possession of the goods |
| Producer (cultivator, processor or manufacturer) | Treas. Reg. 1.471-3(c) and 1.471-11 (full absorption) | Direct production costs and a share of indirect production costs, as those regulations define them |
| Either, after 1986 rules | Section 263A (uniform capitalization) | Not available to a business inside 280E under the IRS position |
Sources: Chief Counsel Memorandum 201504011; Patients Mutual v. Commissioner, 995 F.3d 671 (9th Cir. 2021).
A Chief Counsel memorandum explains the IRS’s position rather than binding taxpayers, and how a particular business’s costs are classified is a determination for its tax advisor. The point for retirement plans is narrower: where employees work in production, whether costs connected to their compensation are inventoriable is the kind of classification question that changes the tax result.
When a second business stays outside 280E
Section 280E applies to a trade or business that “consists of” trafficking. The courts have used that wording to ask whether a company runs one business or two, and the answer turns on how the activities are organized and charged for.
Two businesses
In CHAMP (2007), the Tax Court found that a California organization whose primary purpose was caregiving, with extensive counseling and support services, and whose secondary purpose was providing medical marijuana, carried on more than one trade or business after considering the degree of economic relationship between the two, as the Ninth Circuit later described the decision. Section 280E reached the marijuana activity, not the separate caregiving business.
One business with amenities
In Olive v. Commissioner (2015), the Ninth Circuit held that a San Francisco dispensary offering free services alongside its sales had only one business: selling marijuana. The court used a bookstore analogy: free coffee and seating do not make a bookstore a second business, but a café that sells food and drinks can be.
| Question | Points toward one business | Points toward a separate business |
|---|---|---|
| Is the other activity charged for separately? | Offered free or bundled with product sales (Olive) | Sold for its own price, like the café in the Olive court’s example |
| What is the primary purpose? | The other activity supports selling marijuana | The other activity stands on its own |
| How closely are the activities related economically? | Closely interdependent | Economically distinct enough to be treated separately |
Sources: Olive v. Commissioner, 792 F.3d 1146 (9th Cir. 2015), describing Californians Helping to Alleviate Medical Problems, Inc. v. Commissioner, 128 T.C. 173 (2007).
For a retirement plan, the practical consequence is that a company with genuinely separate businesses may have employees whose plan costs sit outside 280E, while costs for employees in the trafficking business remain inside it. How that line is drawn for a specific company is a question for its tax advisor, and the plan’s records by employee and role are what any allocation would draw on.
How 280E affects a cannabis company’s 401(k)
Section 280E is a statute about the business’s deductions and credits. It does not prevent a cannabis business from sponsoring a qualified retirement plan, and it touches the plan in three distinct places that are worth keeping separate.
Employee contributions are not affected
Employee deferrals come out of the employee’s own wages. Under the IRS 401(k) plan overview, pre-tax elective deferrals are generally not subject to federal income tax withholding when deferred and are not reported as taxable income on the employee’s return, and Roth deferrals follow their own rules. Section 280E disallows deductions and credits of the trafficking business; it does not address the employee’s own tax treatment. Employees of cannabis companies receive the same tax treatment on their contributions as employees anywhere else.
Employer contributions and plan expenses: the deduction question
Matching and profit-sharing contributions, and plan administration fees the business pays, are business expenses. For a business inside 280E they fall under the general disallowance unless they are properly part of cost of goods sold, which under the IRS’s position is possible only for costs the applicable inventory regulations treat as inventoriable. Since April 28, 2026 the analysis splits by license: activity under a qualifying state medical license is in Schedule III, and Treasury has announced that rescheduling is expected to generally remove 280E as a barrier for that activity, subject to future IRS and Treasury guidance, while adult-use activity remains in Schedule I and inside 280E.
Businesses that do not traffic in marijuana are outside 280E’s text. Where labor is genuinely part of production, how contribution cost is allocated is a determination for a CPA experienced with cannabis businesses.
Startup and contribution credits: read the license first
SECURE 2.0 expanded the credits available to employers with 100 or fewer eligible employees that start a new plan: a startup cost credit of up to $5,000 a year for three years, an employer contribution credit of up to $1,000 per employee, and a $500 auto-enrollment credit, all claimed on Form 8881 and described in the Form 8881 instructions. Section 280E disallows credits as well as deductions. A plant-touching business whose activity remains in Schedule I therefore generally cannot claim these credits, and the same disallowance applies to other federal business credits, such as the research credit, for that activity. For activity under a state medical license, Treasury has announced that rescheduling is expected to generally remove 280E as a barrier, subject to future IRS and Treasury guidance, and businesses that do not traffic in marijuana are outside its text. Our guide to retirement plan tax credits and deductions explains how each credit is calculated.
How 280E treats each part of a 401(k)
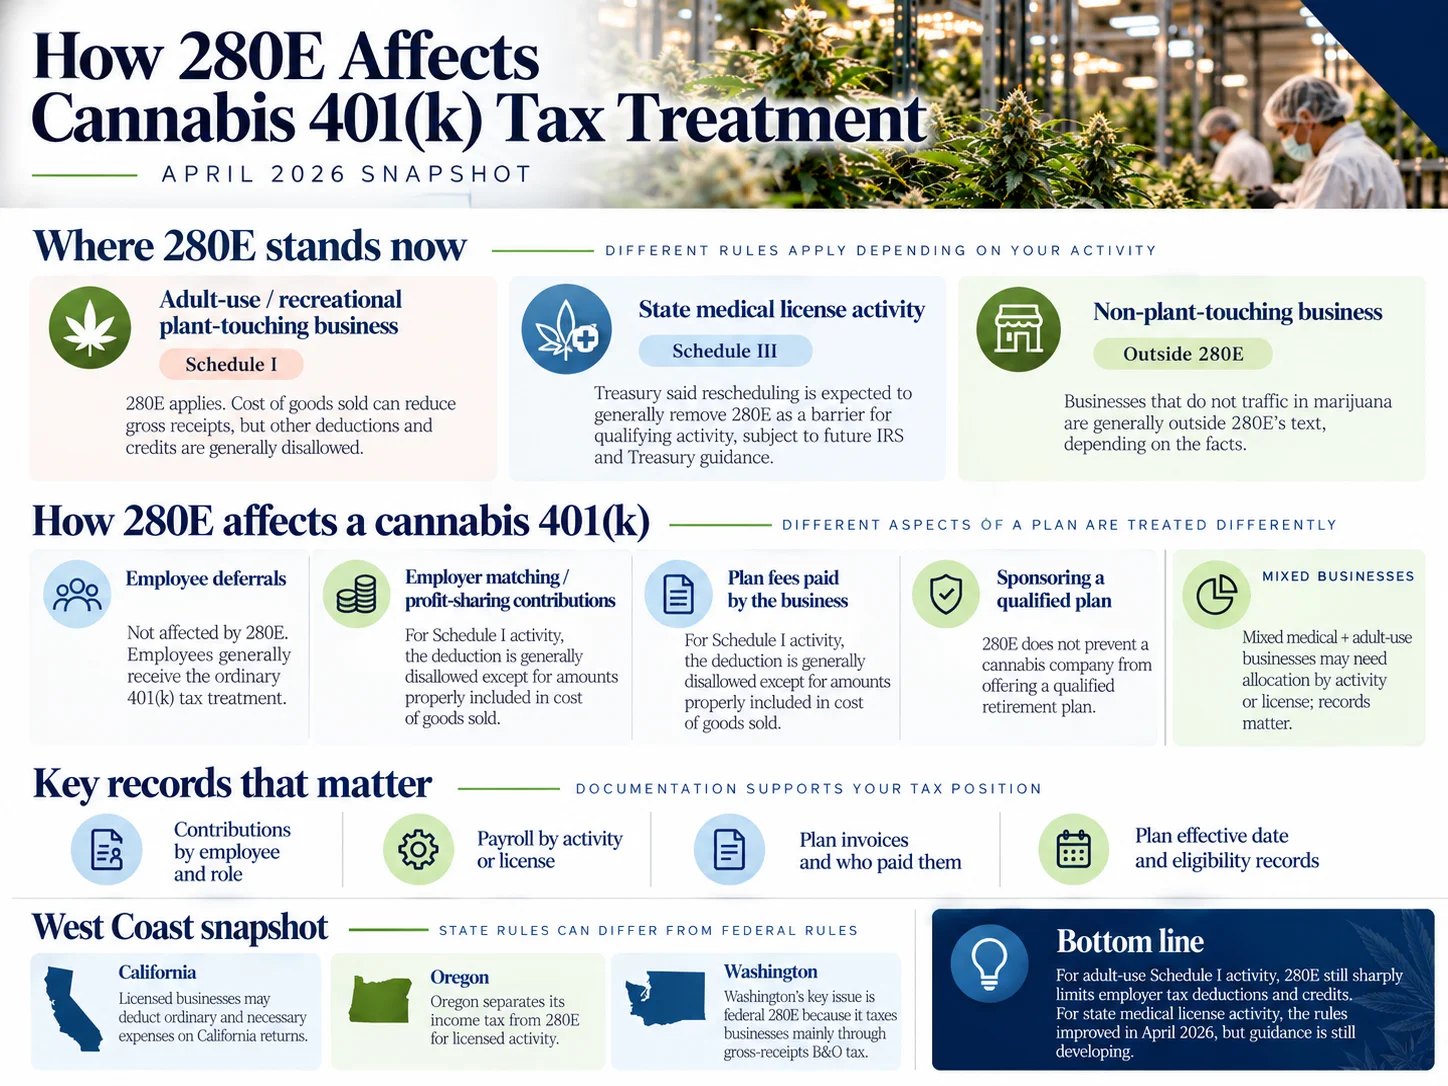
| Plan item | Adult-use activity (Schedule I) | State medical license activity (Schedule III) | Business not trafficking in marijuana |
|---|---|---|---|
| Employee pre-tax deferrals | Ordinary employee tax treatment | Ordinary employee tax treatment | Ordinary employee tax treatment |
| Employer matching and profit-sharing contributions | Deduction disallowed except amounts properly in cost of goods sold | 280E expected to be generally removed as a barrier, subject to future guidance | Ordinary deduction rules |
| Plan fees paid by the business | Deduction disallowed except amounts properly in cost of goods sold | 280E expected to be generally removed as a barrier, subject to future guidance | Ordinary deduction rules |
| Startup, contribution and auto-enrollment credits | Disallowed | 280E expected to be generally removed as a barrier, subject to future guidance; the credits’ own eligibility rules apply | The credits’ own eligibility rules apply |
| Sponsoring a qualified plan | Not restricted by 280E | Not restricted by 280E | Not restricted by 280E |
Based on 26 U.S.C. 280E, the Treasury announcement of April 23, 2026, IR-2024-177 and the IRS 401(k) plan overview. Mixed businesses apply each column to the relevant activity, subject to the apportionment guidance Treasury has announced.
The plan records behind these determinations
Every tax position described above rests on records, and a retirement plan generates several of them. Which ones matter depends on the business, but for a cannabis employer they typically include:
- Contributions by employee and role. Employer contributions for each participant, alongside that employee’s role, which is the starting point for any question about whether a cost relates to production, to retail activity or to administration.
- Payroll by activity or license. For businesses with medical and adult-use activity, wages and contributions associated with each license, which is the information an apportionment rule would work from.
- Plan invoices and who paid them. Administration and recordkeeping fees paid by the business, as distinct from fees charged to participant accounts.
- The plan’s effective date and eligibility records. The information Form 8881 draws on for any credit the business is in a position to claim.
Our guide to cannabis retirement plan administration covers how these records are produced and maintained through the plan year.
Medical and adult-use: where the line runs now
Treasury’s announcement describes two elements of the forthcoming guidance. First, for businesses with more than one activity, the guidance is expected to clarify how 280E applies only to activities involving Schedule I or II substances, for example by apportioning expenses. Second, it is expected to include a transition rule under which rescheduling generally first applies for the business’s full taxable year that includes the order’s effective date, for activities that no longer involve Schedule I or II substances. For a calendar-year business, the year that includes April 28, 2026 is 2026.
The announcement does not describe relief for tax years before that one. In 2024, while the rescheduling proposal was pending, the IRS stated that refund claims based on 280E no longer applying were not valid because marijuana remained in Schedule I until a final rule was published (IR-2024-177). Whether any earlier year can be revisited is a question to take to a tax advisor once the guidance is published.
For a business with both medical and adult-use licenses, records matter more than they did before. Expenses that can be traced to one activity, and a consistent method for shared costs such as rent, administration and benefits, are what an apportionment rule will be applied to. Retirement plan costs are one of those shared costs.
What the pending rescheduling hearing could change
The April 2026 order did not end the rescheduling process. A Drug Enforcement Administration administrative hearing on moving marijuana more broadly to Schedule III began on June 29, 2026, according to the Federal Register notice of hearing, and its status is posted on the DEA’s rescheduling page. Until a final rule takes effect, adult-use marijuana remains in Schedule I and inside 280E. If a broader rule is adopted, the question for adult-use activity would move to the effective date and guidance that accompany that rule. Our Schedule III article follows what rescheduling means for cannabis 401(k) plans in more detail.
State taxes can differ: California, Oregon and Washington
Section 280E is federal. States decide for themselves whether to follow it, and California is an example of a state that does not for licensed businesses.
California
According to the California Franchise Tax Board, licensed cannabis businesses may deduct cost of goods sold and all ordinary and necessary business expenses, such as rent and wages, on their California returns, while unlicensed businesses may deduct only cost of goods sold. The Board also notes that the California research credit follows federal law, so its availability to cannabis businesses may be limited by federal rules.
California’s High-Road Cannabis Tax Credit, available for taxable years 2023 through 2027 to retailer and microbusiness licensees, requires qualifying businesses to provide full-time employees with retirement benefits, which the Board lists as including a 401(k), SEP, SIMPLE IRA, defined benefit plan or automatic enrollment payroll deduction IRA. The Board states that participating in CalSavers does not meet that requirement, and that the credit’s full allocation has been reserved and its reservation system is closed. California employers without a plan are subject to the state’s retirement mandate, covered on our California mandate page.
Oregon
Oregon also separates its income tax from 280E for licensed businesses. For personal income tax, ORS 316.680(1)(i) subtracts from federal taxable income any federal deduction the taxpayer would have been allowed for the production, processing or sale of marijuana items authorized under Oregon’s licensing statutes, but for 280E. For corporations, ORS 317.363 provides that 280E applies to trafficking in Schedule I or II substances other than conduct authorized under those same statutes. Oregon employers without a plan are subject to the OregonSaves mandate, covered on our Oregon mandate page.
Washington
Washington works differently because of how it taxes businesses. According to the Washington Department of Revenue, most businesses pay the business and occupation (B&O) tax, a gross receipts tax under which businesses cannot deduct expenses such as labor or materials. Washington does not currently have an individual income tax, although the Department reports that a 9.9% tax on individuals with adjusted gross income above $1 million, established by the 2026 Legislature, takes effect January 1, 2028. For a Washington cannabis business today, the 280E question is therefore a federal one. Washington employers without a plan are covered by the Washington Saves program described on our Washington mandate page.
| Jurisdiction | Income tax treatment of licensed cannabis business expenses | Source |
|---|---|---|
| Federal | 280E disallows deductions and credits for Schedule I or II trafficking; cost of goods sold still reduces gross receipts; state medical license activity moved to Schedule III in April 2026 | 26 U.S.C. 280E; U.S. Treasury |
| California | Licensed businesses may deduct cost of goods sold and ordinary and necessary expenses; unlicensed businesses only cost of goods sold | Franchise Tax Board |
| Oregon | Deductions barred federally by 280E are subtracted for licensed activity (personal); 280E not applied to licensed activity (corporate) | ORS 316.680(1)(i); ORS 317.363 |
| Washington | No individual income tax before 2028; B&O tax is on gross receipts without expense deductions | Washington Department of Revenue |
Other states set their own rules. The table covers the three West Coast states only.
Questions cannabis employers ask about taxes and 401(k) plans
Can a dispensary deduct its 401(k) contributions?
It depends on its license. For activity that remains in Schedule I, such as adult-use sales, 280E generally disallows the deduction except for amounts properly included in cost of goods sold. For activity under a state medical license, Treasury has announced that rescheduling is expected to generally remove 280E as a barrier for qualifying activity, subject to future IRS and Treasury guidance.
Are employees’ 401(k) contributions affected by 280E?
No. Section 280E addresses the business’s deductions and credits, and employee deferrals are taxed under the ordinary rules the IRS describes for any 401(k) participant.
Can a cannabis company claim the retirement plan startup credit?
Generally no for activity that remains subject to 280E, though businesses should consult tax advisors regarding their specific circumstances. Activity under a state medical license and businesses that do not traffic in marijuana are in a different position, and the credit’s own eligibility rules still apply.
Is cost of goods sold calculated the same way for growers and dispensaries?
No, under the IRS’s position in Chief Counsel Memorandum 201504011. Producers use full-absorption inventory rules, and resellers use the narrower rules for purchased goods, both as they stood when 280E was enacted.
Can a dispensary avoid 280E by offering free services?
Not by that alone. In Olive, the Ninth Circuit held that free amenities offered alongside marijuana sales did not create a separate business. CHAMP reached a different result for a substantial caregiving business with its own purpose and economic role.
Do Oregon and Washington follow 280E?
Oregon does not apply 280E to marijuana activity authorized under its licensing statutes, for personal or corporate income tax. Washington has no individual income tax before 2028 and taxes most businesses on gross receipts, so the 280E question there is federal.
Can a medical cannabis business amend earlier returns now that its activity is in Schedule III?
Treasury’s announcement describes a transition rule for the tax year that includes April 28, 2026 and does not describe relief for earlier years. The IRS’s 2024 statement treated refund claims for earlier years as invalid. This is a question for a tax advisor once the guidance is published.
Where Leading Retirement Solutions fits
Leading Retirement Solutions has worked with cannabis employers since 2017 and launched The Leading Cannabis 401(k)® publicly in 2019. LRS administers retirement plan solutions designed for industries affected by 280E, while tax determinations remain the responsibility of the employer and its advisors. For what a cannabis plan involves from setup onward, see our employer guide to cannabis 401(k) plans and our guide to cannabis retirement plan administration. To talk through a plan, contact our team.
Sources
Every rule described in this article comes from the government and court sources below, each read in September 2026.
Federal statute and rescheduling
-
26 U.S.C. 280EThe disallowance of deductions and credits for a trade or business consisting of trafficking in Schedule I or II controlled substances.Current code text, U.S. House Office of the Law Revision Counsel
-
Treasury, IRS announce process for tax guidance following DOJ final order on medical marijuana reschedulingWhich marijuana moved to Schedule III and which remains in Schedule I; the expected removal of 280E as a bar for qualifying activity; expected apportionment guidance and transition rule.U.S. Department of the Treasury, April 23, 2026
-
Justice Department places FDA-approved and state-licensed medical marijuana in Schedule IIIThe final order and the separate hearing on broader rescheduling.U.S. Department of Justice, April 2026
-
Schedules of Controlled Substances: Rescheduling of Marijuana, notice of hearing, 91 FR 22777The DEA hearing on broader rescheduling beginning June 29, 2026.Federal Register, April 28, 2026
-
Marijuana rescheduling regulatory actionsStatus page for the rescheduling proceedings.Drug Enforcement Administration, checked September 2026
Internal Revenue Service
-
IR-2024-177: Marijuana remains a Schedule I controlled substance; section 280E still applies280E applies in states where sale is legal; cost of goods sold still reduces gross receipts; refund claims invalid while marijuana remained in Schedule I.IRS news releases, June 28, 2024
-
Chief Counsel Memorandum 201504011The IRS position on cost of goods sold under the 1982 section 471 regulations and the reseller and producer distinction.Released January 23, 2015
-
401(k) plan overviewTax treatment of employee pre-tax and Roth deferrals.Last reviewed or updated August 4, 2026
-
Instructions for Form 8881The startup, employer contribution and auto-enrollment credits.Rev. December 2025
Federal courts
-
Olive v. Commissioner, 792 F.3d 1146 (9th Cir. 2015)Free amenities did not create a second business; the bookstore analogy; the court’s description of CHAMP.Filed July 9, 2015
-
Patients Mutual Assistance Collective Corp. v. Commissioner, 995 F.3d 671 (9th Cir. 2021)A reselling dispensary must follow Treas. Reg. 1.471-3(b).Filed April 22, 2021
State sources
-
California Franchise Tax Board: Cannabis industryCalifornia deductions for licensed and unlicensed cannabis businesses; the research credit note.Checked September 2026
-
California Franchise Tax Board: High-Road Cannabis Tax CreditRetirement benefit requirement, qualifying plan types and CalSavers not qualifying.Last updated September 24, 2025
-
ORS 316.680(1)(i)Oregon personal income tax subtraction for deductions barred by 280E.Oregon State Legislature, 2025 edition
-
ORS 317.363Oregon corporate treatment of 280E for licensed activity.Oregon State Legislature, 2025 edition
-
Washington Department of Revenue: Business and occupation taxB&O tax as a gross receipts tax without expense deductions.Checked September 2026
-
Washington Department of Revenue: Income taxNo current individual income tax; the tax effective January 1, 2028.Checked September 2026
Last reviewed . This article describes federal, California, Oregon and Washington rules as stated in the sources listed and will be updated when Treasury and IRS guidance is published.