Which Plans Exempt an Employer From a State Mandated Retirement Plan?
Most state programs exempt an employer that already sponsors a retirement plan. Which plans count is close to identical from state to state, and the step employers miss is not the plan. It is telling the state they have one.
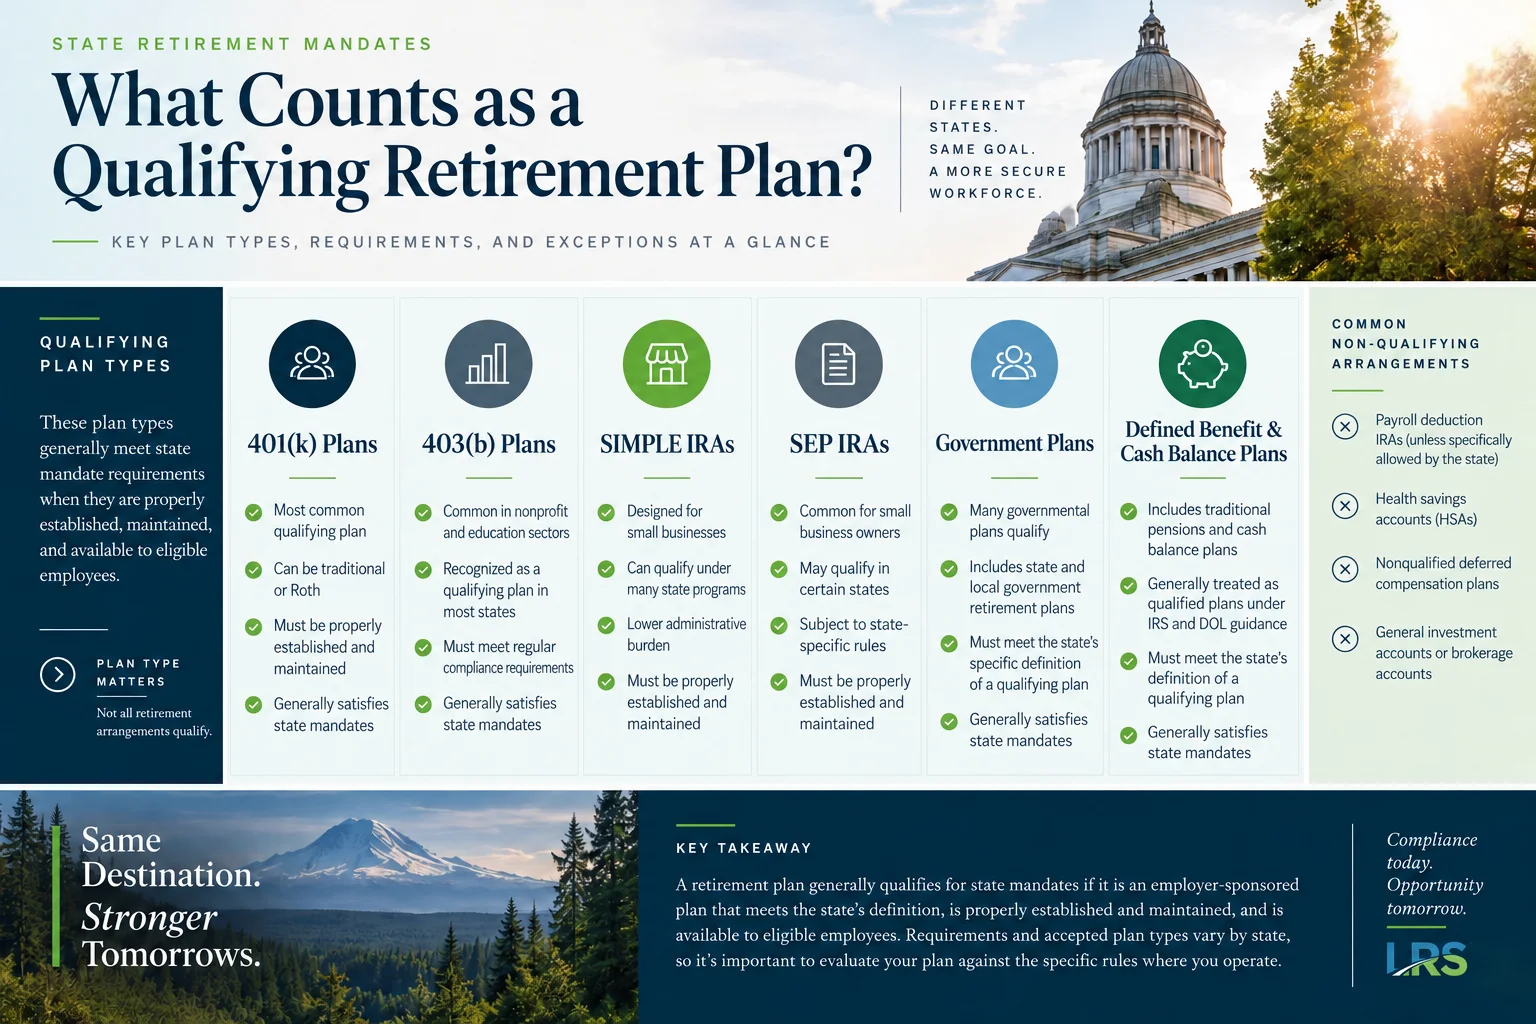
A qualifying retirement plan is generally an employer-sponsored plan under one of a short list of Internal Revenue Code sections: 401(a) qualified plans including profit sharing and defined benefit plans, 401(k) plans including multiple employer and pooled employer plans, 403(a) annuity plans, 403(b) tax-sheltered annuities, 408(k) SEP plans, 408(p) SIMPLE plans, and 457(b) governmental deferred compensation plans. The main variation between states is whether a payroll deduction IRA counts.
Leading Retirement Solutions · Updated for 2026
The list matters less than most employers expect, because almost any conventional employer plan satisfies almost any state program. What causes problems is the part that comes after: several programs require an eligible employer to certify its exemption rather than simply be exempt, and an employer that has a plan but never certifies stays on the state’s list.
This guide covers which plan types qualify, why a 401(k) is not a state retirement plan even though it satisfies one, how exemption is claimed, which employers and employees are counted, and what multi-state employers face. Deadlines and thresholds change as programs come online, so those live on our state retirement mandate map and the individual state pages behind it, which are kept current. This article is general information rather than advice on a particular employer’s situation.
Which Plans Qualify
State programs describe qualifying plans by Internal Revenue Code section rather than by product name, which is why the lists look similar from one state to the next. The IRS overview of types of retirement plans covers each of these structures.
| Plan type | Code section | Notes |
|---|---|---|
| Qualified plan, including profit sharing and defined benefit | 401(a) | The general category of employer-sponsored qualified plans |
| 401(k), including multiple employer and pooled employer plans | 401(k) | The most common route, and the one most state lists name first |
| Qualified annuity plan | 403(a) | Listed alongside 403(b) in most state programs |
| Tax-sheltered annuity | 403(b) | Available to certain tax-exempt and educational employers |
| Simplified Employee Pension, or SEP | 408(k) | Employer-funded, with its own contribution rules |
| SIMPLE IRA or SIMPLE 401(k) | 408(p) | Designed for smaller employers |
| Governmental deferred compensation plan | 457(b) | Listed by most, though relevant to a narrower set of employers |
| Payroll deduction IRA with automatic enrollment | n/a | Accepted by some states and excluded by others. The one item that genuinely varies |
Two points are worth drawing out of that table. Multiple employer plans and pooled employer plans sit inside the 401(k) line rather than forming a separate category, so a small employer joining a pooled employer plan is generally treated the same as one sponsoring its own. And a safe harbor 401(k) is a 401(k), so nothing about a safe harbor design changes its status for state purposes.
The one real variation: payroll deduction IRAs
Where states differ is whether a payroll deduction IRA counts as a qualifying plan. Some accept one with automatic enrollment. Others exclude payroll deduction IRAs from the qualifying list entirely, on the reasoning that the state program is itself a payroll deduction IRA. Because this is the one item that genuinely varies, it is the one worth checking against the state page for each state where a company has employees rather than assuming.
If a company sponsors a 401(k), 403(b), SEP, SIMPLE or a 401(a) plan, it is very likely to satisfy every state program it encounters. If it relies on a payroll deduction IRA, whether it qualifies depends on the state.
Is a 401(k) a State Retirement Plan?
No, and the distinction is worth stating because the phrase gets used both ways. A state retirement plan, in this context, means the program the state itself administers. Those programs are generally Roth IRAs funded by employee payroll deductions, with automatic enrollment and a default contribution rate, and the employer’s role is limited to registering, submitting employee information and remitting deductions. Employers do not contribute.
A 401(k) is an employer-sponsored plan governed by the Internal Revenue Code and, in most cases, ERISA. The employer sponsors it, may contribute to it, chooses the design, and carries the administrative and fiduciary responsibilities that come with it. Sponsoring one is what generally makes an employer exempt from the state program, which is the opposite relationship from the one the phrase suggests.
| State program | Employer-sponsored plan | |
|---|---|---|
| Who administers it | The state, through a program provider | The employer, with its service providers |
| Account type | Generally a Roth IRA in the employee’s name | A plan account under the employer’s plan |
| Employer contributions | Not permitted | Permitted, and a design choice |
| Employee enrollment | Automatic, with the ability to opt out | Set by the plan document, and automatic enrollment may be required for newer plans |
| Contribution limits | IRA limits apply | Plan limits apply, which are higher |
| Employer’s ongoing role | Submit employee information and remit deductions | Sponsor the plan, with administration and fiduciary duties |
Having a Plan Is Not the Same as Being Exempt
This is the part that generates letters, and it is the part almost no article covers.
Several programs require an eligible employer that already sponsors a plan to say so, using an access code the program mails or emails to the business. OregonSaves states that employers who provide a qualified retirement plan or have no W-2 employees should certify their exemption using their access code, and the Oregon state page carries the current position there. CalSavers operates an employer portal where a business enters its federal EIN or TIN and its access code to register or request an exemption, and the California state page carries that program’s detail.
Until that step is completed, the state’s records generally show an eligible employer that has not registered. Depending on the program, the consequence is usually a sequence of notices rather than an immediate penalty, but the notices continue, and in some states enforcement is handled by the revenue authority. The Illinois Department of Revenue publishes its own page on Secure Choice program enforcement, which sets out that employers meeting the thresholds must either offer a qualifying plan or facilitate the program. The Illinois state page carries the current requirement.
The practical sequence is: sponsor a qualifying plan, locate the access code the program sent, certify the exemption, and keep a record of the confirmation. An employer that changes providers or terminates a plan may also need to revisit that certification, because the exemption follows the plan rather than the company.
Which Employers and Which Employees Are Counted
Thresholds vary, and the way employees are counted varies with them. A few patterns repeat across programs.
- Employee count is usually an average rather than a headcount on one day. CalSavers, for example, describes eligibility as based on the average number of employees reported to the state employment department across the previous year’s filings.
- W-2 employees are generally what count. Businesses with no W-2 employees, and those employing only the owners, are commonly outside the requirement.
- Time in business can matter. Some programs apply only to employers that have operated for a minimum period, which is why a new business may not be eligible in its first years.
- Some categories sit outside the programs entirely. Government entities, religious organizations and tribal organizations are commonly excluded, alongside employers that sponsor a plan.
Because those definitions are set by each program rather than by a federal standard, the count that matters is the one the state uses, not the one on an internal headcount report. The state pages behind our mandate map carry the current threshold for each program.
Employers With Staff in More Than One State
A company with employees in four mandate states faces four separate programs, each with its own registration, its own thresholds and its own deadlines.
One qualifying plan can often help satisfy requirements across multiple states, although separate registration or exemption procedures may still apply. That is the practical argument employers weigh.
The comparison is rarely one plan against one program. It is one plan against several facilitation obligations running in parallel, each of which involves payroll deductions, employee records and its own deadlines. Our guide to which states have retirement plan mandates covers where those obligations currently exist.
Where an employer does sponsor a plan, the exemption still has to be claimed with each program separately. One plan does not certify itself in four states.
Choosing Between the State Program and Your Own Plan
Both routes satisfy the requirement. They differ in what the employer takes on and what employees receive.
| Consideration | State program | Own plan |
|---|---|---|
| Satisfies the requirement | Yes | Yes |
| Employer contributions or match | Not available | Available if the employer chooses |
| Owner participation | Through the individual’s own IRA limits | Through the plan, at plan limits |
| Plan design control | None, the program is set by the state | The employer designs it |
| Federal filing and testing | Not carried by the employer | Applies, and is generally handled by the plan’s providers |
| Multi-state employers | Separate facilitation in each state | One plan can often help satisfy several states, though each exemption is claimed separately |
An employer weighing the two is generally comparing an arrangement it does not control against one it designs. Where recruitment, employer contributions or owner participation matter, those are only available in an employer-sponsored plan. Where the priority is meeting the requirement with the least involvement, the state program is built for that. Our overview of defined contribution plans covers what the employer-sponsored side involves, and starting a new plan sets out the process.
What Sponsoring a Plan Involves After the Exemption
Choosing a plan resolves the state requirement and starts a set of federal obligations that the state program does not carry.
- An annual return, generally the Form 5500 or 5500-SF, covered in our guide to finding and reading a Form 5500.
- Annual nondiscrimination and coverage testing, depending on the design.
- Participant notices on their own schedules before each plan year.
- Deposit timing for employee deferrals, which runs through payroll rather than the plan.
- A fidelity bond covering persons who handle plan funds, covered in our guide to ERISA fidelity bonds.
Most of that work sits with the plan’s service providers rather than the employer, through plan administration and recordkeeping, and the deduction side runs through payroll integration. It is worth knowing it exists before choosing, because it is the substantive difference between the two routes.
Deadlines and Current Requirements
Registration deadlines, employer size thresholds and program launch dates change as new programs come online and existing ones expand to smaller employers. Rather than repeat them here, where they would age, they are maintained on the state retirement mandate map and the state pages behind it, with the current position for each state.
Programs are also renamed and restructured. An employer that received correspondence under one program name may find it operating under another, which is another reason to check the current state page rather than an older letter.
What the State Programs Actually Do
Choosing between the two routes is easier with a clear picture of what the state route involves, and the programs are more similar to each other than they are different.
The account and the enrollment
Most programs use a Roth IRA held in the employee’s own name. Eligible employees are enrolled automatically after a notice period, at a default contribution rate set by the program, and many programs increase that rate by one percentage point a year up to a ceiling. Employees may opt out at any time, change their rate, or opt back in later. The account belongs to the employee and travels with them when they change jobs, which is one of the design goals behind the programs.
What the employer does, and does not do
The employer registers the business, submits employee information, and remits payroll deductions. Employers do not contribute to these accounts and generally do not select investments or serve as a fiduciary for them. Program participation is typically at no direct cost to the employer, with account-level fees borne by the saver.
The Roth income question
Because most programs use a Roth IRA, the ordinary Roth IRA eligibility and contribution rules apply to the employee’s account, including the income limits that restrict who may contribute and the annual IRA contribution limit, which is lower than the limit in an employer plan. An employee whose income exceeds the Roth threshold may need to opt out or address an excess contribution, and that is the employee’s responsibility rather than the employer’s. The current figures are in our guide to IRS contribution limits.
What Happens If an Employer Does Nothing
The programs are enforced, and the pattern is consistent even though the amounts are not. Requirements and enforcement mechanisms may vary by jurisdiction.
An eligible employer that neither registers nor certifies an exemption generally receives a sequence of notices, followed by penalties assessed per eligible employee, often escalating for continued non-compliance. In some states the assessment sits with the tax authority rather than with the retirement program. The Illinois Department of Revenue publishes its own page on program enforcement for that reason.
Two things are worth separating. An employer that has no plan and has not registered is out of compliance with the requirement. An employer that has a plan and has not certified is compliant on the substance and unrecorded on the paperwork. The second is the more common situation, and it is resolved by completing the certification rather than by changing anything about the plan.
Situations That Confuse Employers
A plan that does not cover everyone
Plans commonly exclude employees who have not met an age or service condition. Whether that affects the exemption is a question for the specific program, and it is one of the points worth confirming on the state page rather than assuming, particularly where a plan uses the longest eligibility conditions the Code permits.
A plan sponsored through a PEO or a pooled arrangement
Where employees participate through a professional employer organisation or a pooled employer plan, a qualifying plan generally exists, but the entity that sponsors it may not be the entity the state has on file. That mismatch is a common reason a company that believes it is covered continues to receive notices.
A company with employees in a state and a plan in another
Plans are not state-specific. A plan sponsored by a company headquartered in one state generally covers its employees wherever they work, so the exemption question turns on whether the employees in the mandate state are eligible for the plan, not on where the plan was established.
A plan that was recently terminated
The exemption follows the plan. An employer that terminated a plan, or allowed one to lapse, may become eligible for the state program again, and the certification on file will no longer reflect the position.
A new business
Some programs apply only to employers that have operated for a minimum period, so a company in its first year or two may not yet be eligible. That is a deferral rather than an exemption, and the requirement generally arrives with the anniversary.
The Federal Tax Credits That Change the Comparison
An employer weighing its own plan against the state program is often comparing the administrative load of each. There is a second factor that only applies on one side of that comparison.
Under Internal Revenue Code section 45E, an eligible employer starting its first plan may claim a credit against qualified startup costs. The IRS instructions to Form 8881 state that eligible employers with 1 to 50 employees are eligible for a credit of 100% of qualified startup costs, subject to limitation, and that the credit for eligible employers with 51 to 100 employees remains at 50%. SECURE 2.0 added a further credit based on employer contributions, and a separate credit relating to military spouse participation.
These credits apply to an employer-sponsored plan. They do not apply to facilitating a state program, because there are no employer costs or contributions to credit. Whether a specific employer qualifies, and for how much, depends on headcount, on whether it maintained a plan previously, and on the limits in the form instructions, so it is a question for the company’s tax advisor rather than a figure to assume.
Common Questions
What is a qualifying retirement plan for a state mandate?
Generally an employer-sponsored plan under Internal Revenue Code section 401(a), 401(k), 403(a), 403(b), 408(k) SEP, 408(p) SIMPLE or 457(b). Multiple employer plans and pooled employer plans are included within the 401(k) category. Whether a payroll deduction IRA counts varies by state, and it is the one item on the list worth checking state by state.
Does a 401(k) exempt my business from the state program?
In general, yes. Sponsoring a qualifying plan is the basis on which employers are exempt from these programs. In several states the exemption still has to be claimed, using an access code the program sends to the business, so sponsoring the plan and being recorded as exempt are two separate steps.
Is a 401(k) a state retirement plan?
No. A state retirement plan means the program the state administers, generally a Roth IRA funded by employee payroll deductions with automatic enrollment, where the employer facilitates but does not contribute. A 401(k) is an employer-sponsored plan under the Internal Revenue Code and usually ERISA, and sponsoring one is what generally makes an employer exempt from the state program.
How do I certify an exemption from a state retirement program?
Through the program’s employer portal, using the access code it sent to the business along with the federal EIN. OregonSaves directs employers with a qualified plan or no W-2 employees to certify their exemption that way, and CalSavers uses an employer portal where a business can register or request an exemption. Keeping the confirmation on file is worthwhile.
What happens if I have a plan but never registered the exemption?
The program’s records generally continue to show an eligible employer that has not registered, so notices continue to arrive. In some states enforcement sits with the revenue authority. Certifying the exemption is usually straightforward once the access code is located, and programs publish a way to request a replacement code.
Does a SIMPLE IRA or a SEP satisfy a state mandate?
Both appear on the qualifying list in the states that publish one, as plans under Internal Revenue Code sections 408(p) and 408(k). They carry their own contribution and eligibility rules, which differ from a 401(k), so the choice between them is a plan design question rather than a compliance one.
Does a payroll deduction IRA count as a qualifying plan?
It depends on the state. Some programs accept a payroll deduction IRA with automatic enrollment as qualifying. Others exclude payroll deduction IRAs from the list, since the state program is itself a payroll deduction IRA. This is the one item where the state-by-state answer genuinely differs.
Do pooled employer plans satisfy state mandates?
Where a state lists multiple employer plans among its qualifying options, that generally includes pooled employer plans, which several small employers use to satisfy a requirement together. The arrangement is a 401(k) for these purposes.
We have employees in several states. Do we need a plan in each?
One qualifying plan can often help satisfy requirements across multiple states, although separate registration or exemption procedures may still apply. The exemption has to be claimed with each program separately, because one plan does not certify itself in four states.
Are small employers exempt?
Thresholds vary by program and have generally moved downward as programs expand. Businesses with no W-2 employees, and those employing only the owners, are commonly outside the requirement. The current threshold for each state is on that state’s page.
What if we terminate the plan later?
The exemption generally follows the plan. An employer that terminates a plan, or lets one lapse, may become eligible for the state program again and should expect the certification to need revisiting.
Where do I find the current deadline for my state?
On the state page for each state where the company has employees. Deadlines and thresholds change as programs expand, so the map and the state pages behind it carry the current position rather than this article.
What are the penalties for not offering a retirement plan?
Penalties are set by each state and are generally assessed per eligible employee, often escalating where non-compliance continues. In several states the assessment is handled by the tax authority rather than by the retirement program. An employer that already sponsors a plan and has simply not certified its exemption is in a different position from one that has neither.
Can I claim a tax credit for starting a plan instead?
An eligible employer starting its first plan may be able to claim the small employer pension plan startup costs credit under Internal Revenue Code section 45E. The IRS instructions to Form 8881 state that employers with 1 to 50 employees may claim 100% of qualified startup costs, subject to limitation, and 50% for employers with 51 to 100 employees. The credits do not apply to facilitating a state program.
Our employees participate through a PEO. Are we exempt?
A qualifying plan generally exists in that arrangement, but the entity sponsoring it may not be the entity the state has on file, which is a common reason notices continue to arrive at a company that believes it is covered. Confirming which entity is recorded, and certifying the exemption under the right one, usually resolves it.
Current Requirements by State
Each state below links to its own page, where the registration deadline, the employer size threshold and the program’s current status are maintained. Those pages are the current record; this article covers the parts that do not change from state to state.
- California
- Colorado
- Connecticut
- Delaware
- Hawaii
- Illinois
- Maine
- Maryland
- Massachusetts
- Minnesota
- Mississippi
- Missouri
- Nevada
- New Jersey
- New Mexico
- New York
- Oregon
- Rhode Island
- Utah
- Vermont
- Virginia
- Washington
As of September 2026, states not listed do not currently operate a program of this kind, though the list has grown every year since the first programs launched, and legislation is pending in others.
Working Out Which Route Fits
The question is rarely whether a plan qualifies, because almost every conventional employer plan does. It is whether an employer wants the plan it would design or the program the state administers, and whether the exemption has actually been recorded once that choice is made.
Leading Retirement Solutions works with employers on both sides of that decision, including those who started with a state program and later moved to a plan of their own through upgrading an existing arrangement.
Sources and Review
Every substantive claim in this guide traces to a primary source: the federal agency that sets the rule, or the state program that administers it. No payroll vendor, recordkeeper, competitor or aggregator is cited. Each link opens the current version of the page on the issuing body’s own site.
- Internal Revenue ServiceTypes of retirement plansThe plan structures behind each Code section named in the qualifying list.
- Internal Revenue ServicePublication 560, Retirement Plans for Small BusinessSEP, SIMPLE and qualified plan rules for smaller employers.
- Internal Revenue ServiceAbout Form 8881, Credit for Small Employer Pension Plan Startup CostsThe section 45E startup credit percentages and the headcount bands they apply to.
- OregonSavesEmployer program detailsCertifying an exemption with an access code, and what facilitating the program involves.
- CalSaversEmployer portalRegistering or requesting an exemption, and how employee eligibility is counted.
- Illinois Department of RevenueSecure Choice program enforcementEnforcement, and the requirement to either offer a qualifying plan or facilitate the program.
- U.S. Department of Labor, EBSAForm PR, pooled plan provider registrationThe registration regime behind pooled employer plans.
- U.S. Department of Labor, EBSAMeeting Your Fiduciary ResponsibilitiesWhat sponsoring a plan involves once an employer chooses that route.
Leading Retirement Solutions is a third-party administrator serving employers in all 50 states. Provided for general information only and not legal or tax advice. Qualifying plan types, employee counting rules, thresholds, deadlines and enforcement vary by state and change as programs expand. Confirm the current position with the applicable state program or your advisors before acting.
Find out which route fits your business
Leading Retirement Solutions provides plan design, administration, recordkeeping and payroll support for employers across the country.